Surety bonds and guarantees — fact sheet
The instruments we write, the published rate each starts from, the reference criteria, the documents an underwriter needs and how a line is requested.
For contractors, dealer networks, corporate treasurers and their brokers
Guarantees are the line of business FDI Insurance is licensed for. We issue surety bonds and financial guarantees as an insurer rather than as a bank, which means the facility sits outside your borrowing lines and leaves your committed facilities untouched. Every wording is read by an underwriter before it is issued, and every bond is issued by the same entity that carries the risk.
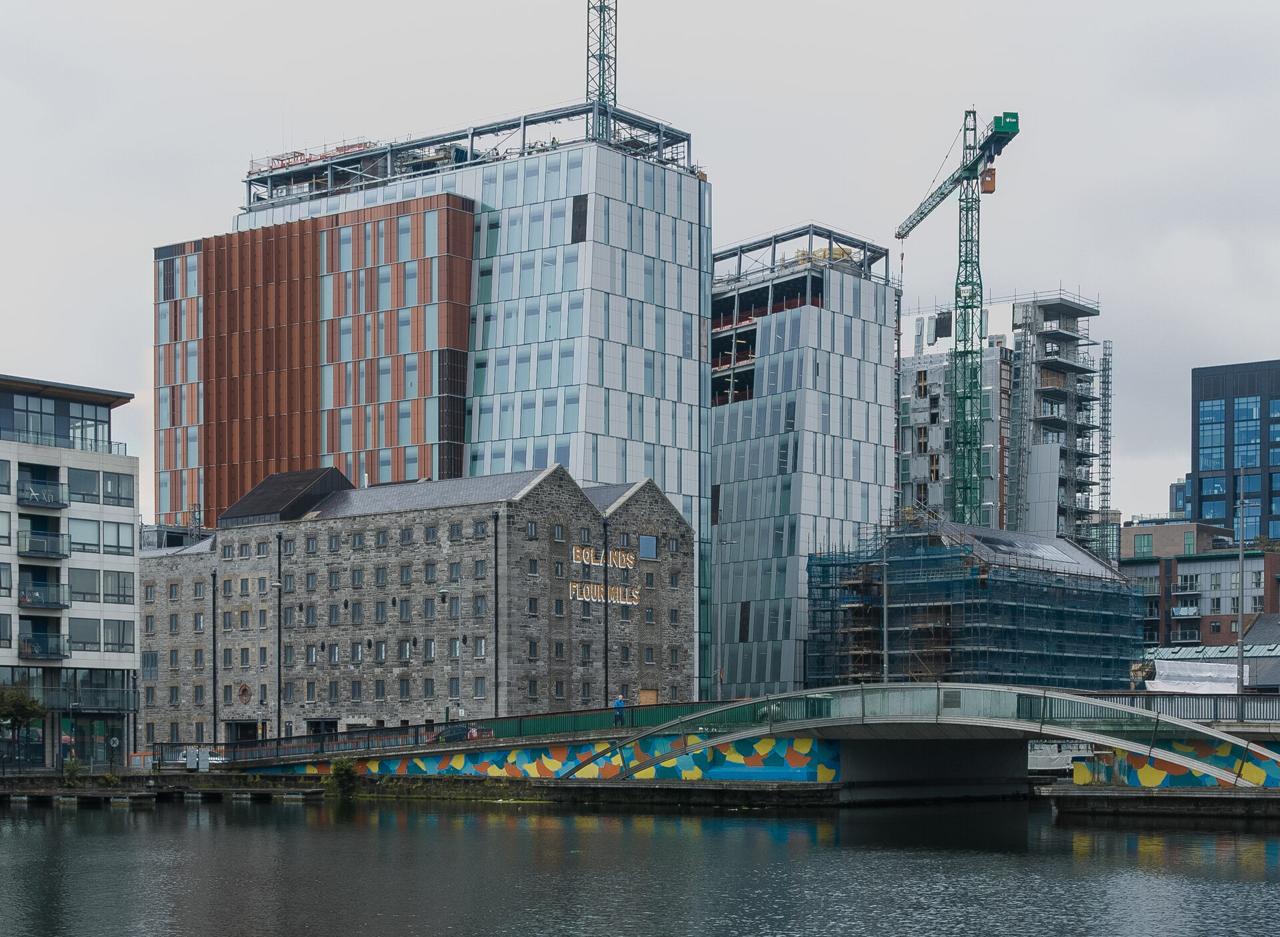
Boland’s Quay, Dublin · William Murphy, CC BY-SA 2.0
12 products
Each product page sets out who it is for, what it does, and the facts a broker needs before recommending it.
Contract surety
Secures an employer against the cost of completing a contract if the contractor fails to perform. Issued on-demand or default-based, in the employer’s preferred wording where it is acceptable to us.
Read moreSurety insurance for Spain
The Spanish surety instrument, written on our own paper under ramo 15 of the DGSFP register: guarantees admitted for the garantía provisional and definitiva in public procurement, for an aplazamiento of tax debt and for grid access and connection — outside the bank facility that funds the work.
Read moreGrid access, permits, auctions, EPC and dismantling
The guarantees a wind, solar or storage project has to post before it earns anything — to secure its grid access and connection point, to the administration that authorises it, to take part in a capacity auction, on the EPC and supply contracts, to the offtaker and for dismantling the plant at the end — written as surety by an insurer, so the sequence is carried by one facility and the bank line that funds construction is left intact.
Read moreContract surety
Lets a supplier take payment up front while giving the buyer recourse if the goods or works are never delivered. Reduces amortises as the contract is performed.
Read moreContract surety
Short-dated bond confirming that a tender is serious and that the bidder will enter the contract on the terms offered. Usually a small percentage of the tender sum.
Read moreContract surety
Replaces cash retention held by the employer with an insurance bond, releasing working capital to the contractor while leaving the employer’s position intact.
Read moreStatutory guarantee
Comprehensive guarantee securing deferred duty, VAT and excise to Revenue or HMRC, so that goods can move under duty suspension without lodging cash.
Read moreCredit
Indemnifies a seller against non-payment by trade debtors through insolvency or protracted default, on a whole-turnover or key-accounts basis.
Read moreCredit
Guarantees a defined payment obligation — a lease stream, a dealer floorplan facility, a deferred consideration — where the beneficiary needs an insurer’s covenant behind a counterparty it cannot fully assess.
Read moreCommercial surety
Stands in place of a cash rent deposit on a commercial lease, so the tenant keeps the deposit in the business and the landlord keeps its security.
Read moreResidential caución, Spain
Cover against unpaid rent on a residential lease in Spain, written as a caución de alquiler: the landlord is indemnified for the months of additional security the lease provides for, the tenant keeps the cash a bank aval or extra months would have tied up, and the legal fianza stays where the law puts it.
Read moreStatutory guarantee
Secures a site restoration or aftercare obligation imposed by a planning authority or the Environmental Protection Agency, for the full statutory aftercare period.
Read moreIndicative pricing
Work out what it costs to have a bond issued on our paper: the premium rate, the fees and the total payable on issue. Every figure updates as you change the form, and the rate build-up underneath shows how each answer moved the price.
Indicative cost
€22,500.00
over 24 months (2 years) · 1.13% of bond value per annum, all in
1.10%p.a. premium rate (110 bps)
This carries the figures above into the enquiry form below, where you can add the contract detail.
Surety is rated on the applicant, not on the beneficiary’s covenant. Each line below multiplies the one above it.
Single premium for the whole term, payable in full on issue, together with the fees. Nothing falls due after issue.
The premium is not paid annually or monthly: whatever the term of the bond, it is paid in full before the bond is issued. For larger bonds only, the desk may agree payment by instalments, on conditions the applicant signs up to — payment undertakings, cheques, deposits or other security — and that is decided case by case, never by this calculator.
Post-issue servicing is charged separately: amendments €150 per endorsement, extensions 0.05% of bond value (minimum €300). Claims are handled without a fee.
Indicative only. This calculator applies our published rates to the answers given. It is not a quotation, does not constitute an offer of insurance, and does not commit FDI Insurance d.a.c. to issuing a bond. Firm terms follow underwriting: audited accounts, the contract or licence documents, the proposed wording and, where required, a counter-indemnity. Bonds are arranged through regulated intermediaries only. FDI Insurance d.a.c. is authorised by the Central Bank of Ireland.
What drives the number
Nothing in the calculator is arbitrary. These are the levers an underwriter actually pulls.
A surety bond is underwritten on the applicant and its counter-indemnity, not on the beneficiary’s covenant. Financial strength moves the rate further than anything else on the form.
An on-demand bond is an unconditional obligation and is priced as one. A conditional bond, where default has to be established first, is our standard form and our cheapest.
The rate is quoted per annum, but the premium for the whole term is paid in full on issue, and a long-dated bond carries a loading because the rate is fixed for the whole of it.
Before any loading or discount, and the same rates quoted on the product pages.
| Bond or guarantee | Standard term | Usually written for | From |
|---|---|---|---|
| Performance Bond | 12–60 months | Typically 10% of contract value | 1.05% p.a. |
| Seguro de Caución | 6–60 months | Garantía definitiva 5% of the award price; deferral and access guarantees in full | 1.05% p.a. |
| Renewable Energy Surety | 12–120 months | The sum per kilowatt the access regulation sets; 10% – 30% on EPC and supply contracts | 1.20% p.a. |
| Advance Payment Guarantee | 6–24 months | 10% – 30% of contract value | 1.20% p.a. |
| Bid & Tender Bond | 3–12 months | 1% – 5% of the tender sum | 1.35% p.a. |
| Retention Bond | 12–36 months | 3% – 5% of contract value | 0.95% p.a. |
| Customs & Excise Guarantee | 12–60 months | Limit assessed by Revenue or HMRC | 0.85% p.a. |
| Financial Guarantee | 6–60 months | Named obligation, up to 100% | 1.50% p.a. |
| Rent Deposit Guarantee | 12–60 months | 3 – 12 months’ rent | 1.30% p.a. |
| Environmental Restoration Bond | 60–360 months | The restoration cost estimate in full | 1.15% p.a. |
Request a firm quotation
Price a bond above and the figures come through to this form. You can also write to us directly.
Common questions
The questions the underwriting desk answers most often, and the answers it gives. Nothing here is an offer of cover — a bond is priced and issued on the submission in front of us.
Documents and forms
Four documents a broker can forward: what we write and at what rate, why an insurer’s bond rather than a bank guarantee, the guarantees a renewable energy project posts, and the questionnaire a company completes to request a line. Each is in English and in Spanish; the questionnaire is a fillable PDF that emails itself to the desk, and can also be completed online.
The instruments we write, the published rate each starts from, the reference criteria, the documents an underwriter needs and how a line is requested.
Why a surety bond or a seguro de caución rather than a bank guarantee: the facility it leaves intact, the cost basis, the acceptance by the administration, the supervised capital behind it.
The sequence from the grid access and connection guarantee to dismantling, who holds each one, when it is released, what the desk needs and the facility that carries the sequence.
The form a company completes to request a bond, a guarantee or a facility — fillable, with a button that emails it to the desk. Also available as an online form.
The documents describe how the desk works and the rates it publishes; none of them is an offer of cover, and the policy wording and schedule, once issued, are the only documents that determine what is covered.
Spain
The same guarantee desk writes ramo 15, caución, and ramo 14, crédito, in Spain under the freedom to provide services: guarantees admitted for the garantía provisional and definitiva, for a tax aplazamiento and for a grid connection, without spending the bank line that funds the work.
Who to talk to
For contractors, dealer networks, corporate treasurers and their brokers. We do not sell direct: the intermediary keeps the client relationship and we underwrite behind it. Everything on this page is issued by an undertaking authorised by the Central Bank of Ireland.
Elsewhere
Onshore and international accounts, insured funds and open architecture.
Annuities, scheme pensions, fixed-term income and drawdown.
Trusts, whole of life cover and professional trustee services.
Group life, income protection, critical illness and employee support.
Lifetime mortgages and later-life buy-to-let lending.