Guarantees & surety
Performance Bond
Secures an employer against the cost of completing a contract if the contractor fails to perform. Issued on-demand or default-based, in the employer’s preferred wording where it is acceptable to us.
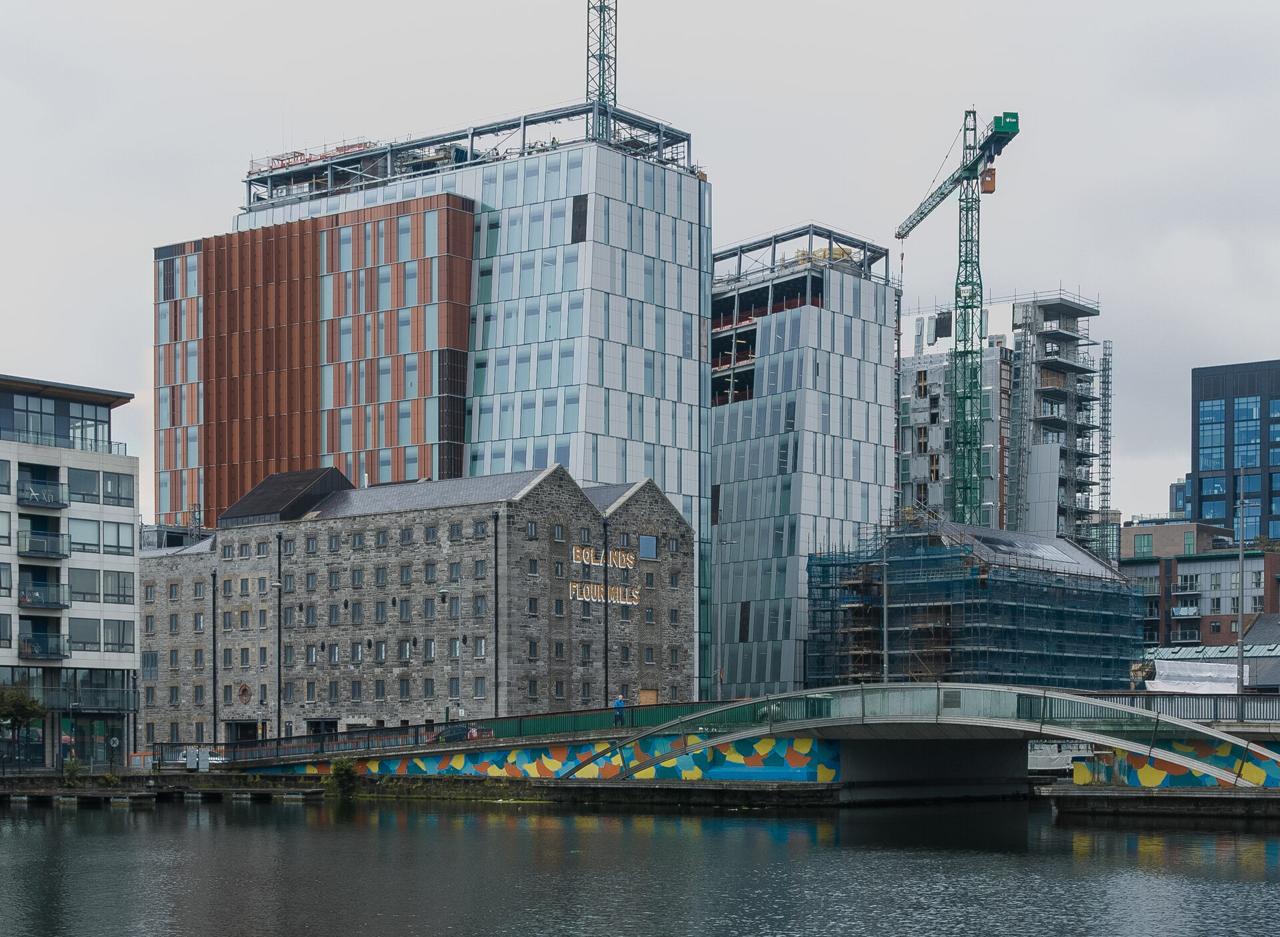
Boland’s Quay, Dublin · William Murphy, CC BY-SA 2.0
Who it is for
Main contractors and sub-contractors bidding public and private works
What it does
- On-demand and conditional (default) wordings
- Typically 10% of contract value, with higher percentages considered on referral
- Bond stays in force to practical completion, or to the end of the defects liability period where required
- Wordings reviewed by an underwriter, not a template checker — amendments come back with reasons
- Sits outside your bank facilities, so committed lines stay available
The product in full
A performance bond is the employer’s answer to a simple question: if this contractor stops, who pays for someone else to finish? The bond is a promise by an insurer to make good the employer’s loss up to a stated maximum — conventionally 10% of the contract sum — if the contractor fails to perform. It is not insurance for the contractor. It protects the employer, at the contractor’s expense, and the contractor signs a counter-indemnity agreeing to reimburse us for anything we pay out.
That structure is why surety is underwritten like credit rather than like property insurance. We are not pricing the chance of an accident; we are forming a view on whether a business can deliver what it has promised, and whether it could repay us if it did not. The balance sheet, the order book, the concentration of that order book in one employer, and the record of finishing on time all matter more than the site.
The wording matters as much as the number. A conditional bond obliges the employer to establish default and prove loss before we pay. An on-demand bond obliges us to pay on a compliant written demand, and to argue about it afterwards — which is a materially different obligation and is priced as one. We read the employer’s form before we issue on it, and amendments come back with reasons.
Literature
Product literature is issued to appointed intermediaries. Ask your underwriter, or request it through the enquiry form.
- Performance bond specimen wordingOn request
- Surety proposal formOn request
- Financial information checklistOn request
How it works
What happens, in order
From the first enquiry to the point the cover, the contract or the facility is in place.
The contract sets the requirement
The tender or the signed contract states the bond percentage, the wording and the expiry — practical completion, or the end of the defects liability period. That clause is the specification we work to.
We underwrite the applicant, not the project
Audited accounts, current management figures, the contract schedule and the aggregate of bonds already outstanding. What we are testing is the covenant behind the counter-indemnity.
A facility is agreed, and bonds draw down against it
Most contractors take an annual surety facility with a total exposure limit. Individual bonds are then issued against it in days rather than weeks, because the credit work is already done.
The bond is issued and the counter-indemnity signed
The company, and where required its parent or directors, signs the counter-indemnity. The bond issues on our own paper, from the entity that carries the risk.
It expires, and the exposure is released
On the expiry trigger in the wording. We ask for the certificate of practical completion or the employer’s release so the facility limit is freed for the next bond.
The numbers
A worked example
Illustrative arithmetic, so the shape of the product is visible rather than described. Nothing here is a quotation or a projection.
A £2.4m contract, bonded at 10%
A regional civil engineering contractor wins a £2.4m water services contract for a local authority. The contract requires a 10% performance bond — £240,000 — on the employer’s own conditional wording, running 30 months to the end of the defects liability period.
The applicant is strong and consistently profitable, with modest gearing, and the parent company signs a counter-indemnity.
- Bond value
- £240,000
- Term
- 30 months
- Indicative premium rate
- 0.94% p.a.
- Premium for the term
- £5,640
- Issuance and arrangement fee
- £250
- Wording review fee
- £350
- Total indicative cost
- £6,240
- Cost as a share of bond value
- 2.60% of bond value
How the rate is built
- Base rate — Performance Bond1.05% p.a.
- Financial strength — Band 2 — strong and consistently profitable−5%
- Security — Parent or director counter-indemnity−10%
- Wording — Conditional — default must be establishedNo adjustment
- Beneficiary — Irish or UK public body, Revenue or HMRCNo adjustment
- Term — 13 – 36 months+5%
Priced by the same function as the bond calculator, so this figure and a quotation for the same inputs cannot disagree. Indicative only — nothing here binds an underwriter.
What the applicant’s balance sheet does to the rate
The same £240,000 bond, the same 30-month term, the same wording — priced across our five financial strength bands.
View these figures as a table
| Value | |
|---|---|
| Band 1 — Band 1 — net worth well above the bond value | 0.83% |
| Band 2 — Band 2 — strong and consistently profitable | 0.99% |
| Band 3 — Band 3 — satisfactory, with some volatility | 1.20% |
| Band 4 — Band 4 — adequate, monitored quarterly | 1.51% |
| Band 5 — Band 5 — newly formed or thinly capitalised | 1.93% |
Suitability
Where the Performance Bond fits
The cases it answers, the cases it does not, and what an underwriter needs before quoting.
It is the right answer when
- The contract requires a bond as a condition of award, and the alternative is a bank guarantee that would consume committed facilities.
- The contractor is bidding regularly and wants a standing facility rather than a negotiation per contract.
- The employer is a public body or a substantial corporate using a recognisable form of wording.
Look at something else when
- The requirement is really for retention to be released — a retention bond is the cheaper instrument.
- The obligation is a payment rather than performance; that is a financial guarantee, underwritten differently.
- The contractor has no audited accounts and no parent able to counter-indemnify.
What we need to quote
- 1.Two years of audited accounts and the most recent management accounts.
- 2.The contract or tender documents, and the bond wording required.
- 3.A schedule of contracts in progress, with values, and of bonds already outstanding.
Questions
What brokers ask us about this product
Does the bond appear in our bank facilities?
No. It is issued by an insurer, not by a lender, so it does not draw on committed lines or overdraft headroom. That is the commercial reason most contractors move surety away from their bank.
Will you issue on the employer’s wording?
Usually, and an underwriter reads it first. Where a clause is unacceptable — an unlimited extension right, for instance — the amendment comes back with the reason, which is generally enough for the employer’s advisers.
What happens if the employer calls the bond?
On a conditional bond we investigate whether default has occurred and what loss flows from it. On an on-demand bond we pay a compliant demand and then look to the counter-indemnity. Either way the contractor is asked for its position immediately.
Can the bond be extended?
Yes, by endorsement, subject to the exposure still being within the facility. An extension carries a further premium for the additional period and a minimum charge.
Request information
Ask us about the Performance Bond
The form reaches an underwriter in Dublin. If you are an intermediary, say so and we will route it to the broker desk.