Avales y caución
Aval de cumplimiento
Protege al comitente frente al coste de terminar un contrato si el contratista incumple. Se emite a primer requerimiento o por incumplimiento acreditado, con el texto que prefiera el comitente siempre que nos resulte aceptable.
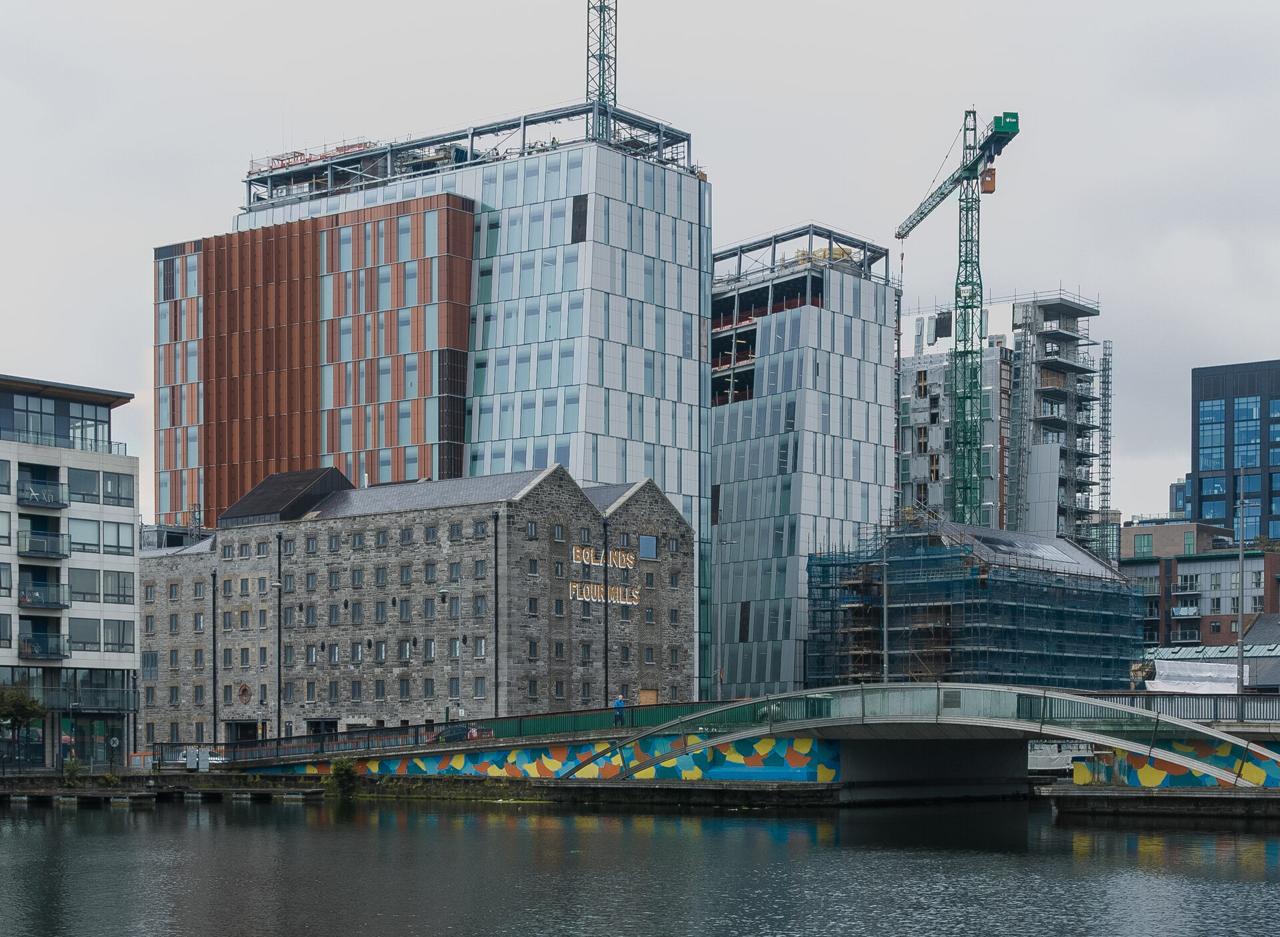
Boland's Quay, Dublín · William Murphy, CC BY-SA 2.0
Para quién es
Contratistas principales y subcontratistas que licitan obras públicas y privadas
Qué hace
- Textos a primer requerimiento y condicionales (por incumplimiento)
- Normalmente el 10% del valor del contrato, con porcentajes superiores estudiados caso por caso
- El aval permanece en vigor hasta la recepción provisional de la obra o, cuando así se exija, hasta el final del periodo de garantía de defectos
- Los textos los revisa un suscriptor, no un verificador de plantillas: las modificaciones vuelven razonadas
- Queda fuera de sus líneas bancarias, por lo que las líneas comprometidas siguen disponibles
El producto en detalle
A performance bond is the employer’s answer to a simple question: if this contractor stops, who pays for someone else to finish? The bond is a promise by an insurer to make good the employer’s loss up to a stated maximum — conventionally 10% of the contract sum — if the contractor fails to perform. It is not insurance for the contractor. It protects the employer, at the contractor’s expense, and the contractor signs a counter-indemnity agreeing to reimburse us for anything we pay out.
That structure is why surety is underwritten like credit rather than like property insurance. We are not pricing the chance of an accident; we are forming a view on whether a business can deliver what it has promised, and whether it could repay us if it did not. The balance sheet, the order book, the concentration of that order book in one employer, and the record of finishing on time all matter more than the site.
The wording matters as much as the number. A conditional bond obliges the employer to establish default and prove loss before we pay. An on-demand bond obliges us to pay on a compliant written demand, and to argue about it afterwards — which is a materially different obligation and is priced as one. We read the employer’s form before we issue on it, and amendments come back with reasons.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Modelo de texto de aval de cumplimientoA petición
- Cuestionario de solicitud de cauciónA petición
- Lista de comprobación de información financieraA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
The contract sets the requirement
The tender or the signed contract states the bond percentage, the wording and the expiry — practical completion, or the end of the defects liability period. That clause is the specification we work to.
We underwrite the applicant, not the project
Audited accounts, current management figures, the contract schedule and the aggregate of bonds already outstanding. What we are testing is the covenant behind the counter-indemnity.
A facility is agreed, and bonds draw down against it
Most contractors take an annual surety facility with a total exposure limit. Individual bonds are then issued against it in days rather than weeks, because the credit work is already done.
The bond is issued and the counter-indemnity signed
The company, and where required its parent or directors, signs the counter-indemnity. The bond issues on our own paper, from the entity that carries the risk.
It expires, and the exposure is released
On the expiry trigger in the wording. We ask for the certificate of practical completion or the employer’s release so the facility limit is freed for the next bond.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
A £2.4m contract, bonded at 10%
A regional civil engineering contractor wins a £2.4m water services contract for a local authority. The contract requires a 10% performance bond — £240,000 — on the employer’s own conditional wording, running 30 months to the end of the defects liability period.
The applicant is strong and consistently profitable, with modest gearing, and the parent company signs a counter-indemnity.
- Importe del aval
- £240,000
- Plazo
- 30 meses
- Tasa de prima indicativa
- 0.94% anual
- Prima por el plazo
- £5,640
- Comisión de emisión y formalización
- £250
- Gastos de revisión del texto
- £350
- Coste indicativo total
- £6,240
- Coste sobre el importe del aval
- 2.60% del importe del aval
Cómo se construye la tasa
- Tasa base — Aval de cumplimiento1.05% anual
- Solidez financiera — Banda 2 — sólida y rentable de forma constante−5%
- Garantía aportada — Contragarantía de la matriz o de los administradores−10%
- Texto — Condicional: hay que acreditar el incumplimientoSin ajuste
- Beneficiario — Organismo público irlandés o británico, Revenue o HMRCSin ajuste
- Plazo — 13–36 meses+5%
Priced by the same function as the bond calculator, so this figure and a quotation for the same inputs cannot disagree. Indicative only — nothing here binds an underwriter.
What the applicant’s balance sheet does to the rate
The same £240,000 bond, the same 30-month term, the same wording — priced across our five financial strength bands.
Ver estas cifras en una tabla
| Valor | |
|---|---|
| Band 1 — Band 1 — net worth well above the bond value | 0.83% |
| Band 2 — Band 2 — strong and consistently profitable | 0.99% |
| Band 3 — Band 3 — satisfactory, with some volatility | 1.20% |
| Band 4 — Band 4 — adequate, monitored quarterly | 1.51% |
| Band 5 — Band 5 — newly formed or thinly capitalised | 1.93% |
Idoneidad
Dónde encaja Aval de cumplimiento
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- The contract requires a bond as a condition of award, and the alternative is a bank guarantee that would consume committed facilities.
- The contractor is bidding regularly and wants a standing facility rather than a negotiation per contract.
- The employer is a public body or a substantial corporate using a recognisable form of wording.
Conviene mirar otra cosa cuando
- The requirement is really for retention to be released — a retention bond is the cheaper instrument.
- The obligation is a payment rather than performance; that is a financial guarantee, underwritten differently.
- The contractor has no audited accounts and no parent able to counter-indemnify.
Lo que necesitamos para tarificar
- 1.Two years of audited accounts and the most recent management accounts.
- 2.The contract or tender documents, and the bond wording required.
- 3.A schedule of contracts in progress, with values, and of bonds already outstanding.
Preguntas
Lo que los corredores nos preguntan sobre este producto
Does the bond appear in our bank facilities?
No. It is issued by an insurer, not by a lender, so it does not draw on committed lines or overdraft headroom. That is the commercial reason most contractors move surety away from their bank.
Will you issue on the employer’s wording?
Usually, and an underwriter reads it first. Where a clause is unacceptable — an unlimited extension right, for instance — the amendment comes back with the reason, which is generally enough for the employer’s advisers.
What happens if the employer calls the bond?
On a conditional bond we investigate whether default has occurred and what loss flows from it. On an on-demand bond we pay a compliant demand and then look to the counter-indemnity. Either way the contractor is asked for its position immediately.
Can the bond be extended?
Yes, by endorsement, subject to the exposure still being within the facility. An extension carries a further premium for the additional period and a minimum charge.
Solicitar información
Consúltenos sobre Aval de cumplimiento
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.