FDI Insurance · Spain
FDI Insurance: caución and crédito in Spain, on an insurer’s own paper
Two complete ramos, active on the DGSFP register since July 2026: guarantees that stand in for a bank line, and credit cover on what a business is owed. Written off the balance sheet we publish in full, every year, to the Central Bank of Ireland.
DGSFP authorisation code: clave L1617 — on the register since 19 July 2026
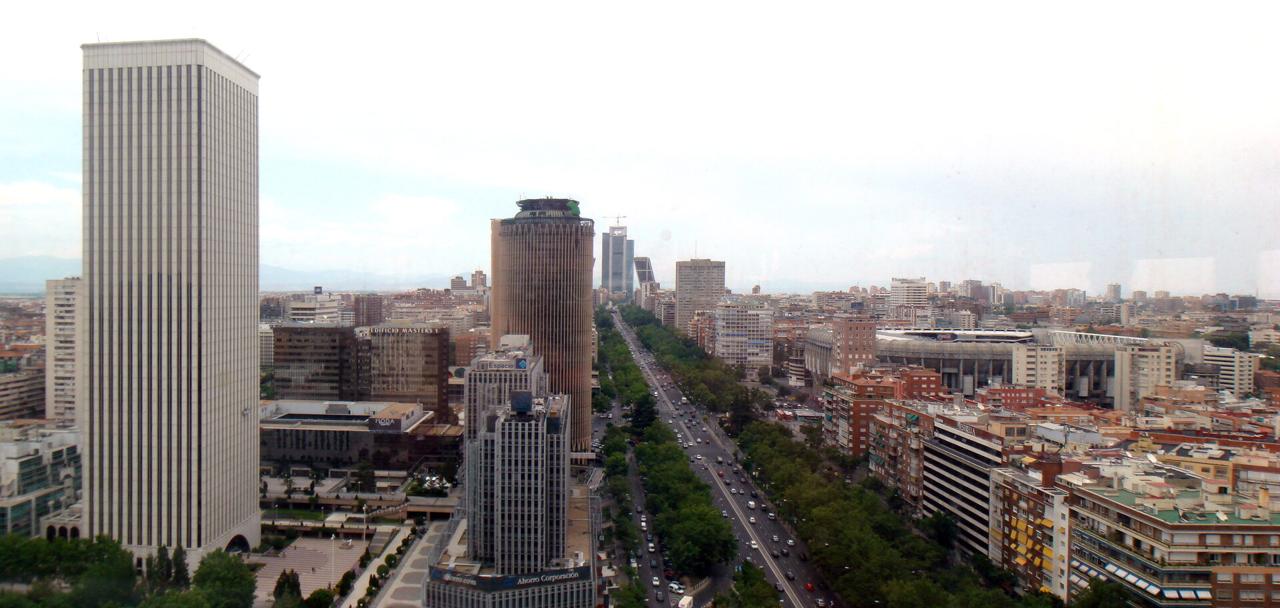
Paseo de la Castellana, Madrid · Álvaro Ibáñez, CC BY 2.0
A guarantee is only ever as good as the balance sheet behind it, and in Spain that is the whole of our proposition. We are an Irish insurance undertaking, authorised and supervised in Dublin, entered on the Spanish register to write ramo 14, crédito, and ramo 15, caución. What that means in practice is that a Spanish contractor, developer or supplier can put an insurer’s guarantee in front of a contracting authority, a tax authority or a counterparty — and keep the bank lines it has fought for, for the work itself.
The seguro de caución is not a second-best aval. It is a guarantee issued by a supervised insurer, admitted where the administration calls for security, lodged where the administration requires it, and paid on the terms written into it. For the company that buys it, the difference from a bank guarantee is not the paper — it is that the limit sits outside the banking relationship. The credit line that was going to fund plant, materials and payroll is still there when the award lands.
That is the whole reason we are in this market. Spanish businesses executing large works, connecting generation to the grid or negotiating a deferral with the tax authority all need security in a form the administration accepts, and they need it without spending the facility that funds the work. We underwrite that security ourselves, on our own capital, and we publish the capital: every filed Solvency and Financial Condition Report since 2019 is on this site, in full, with the cover ratio the Board held it to in each period.
We are also not trying to be everybody’s insurer. Crédito and caución are the two ramos we asked for and the two we write. A specialist book, read by underwriters who do nothing else, is the only way a guarantee gets priced properly rather than declined slowly.
What a seguro de caución is, in law
Under Spanish law the seguro de caución is a contract of insurance in its own right, defined in article 68 of the Ley de Contrato de Seguro: if the policyholder fails to meet a legal or contractual obligation, the insurer indemnifies the beneficiary the policy names, and everything the insurer pays is owed back to it by the policyholder. Three parties and fixed roles — the tomador who buys the cover, the asegurado who is paid, and the insurer between them — which is why the beneficiary never deals with a bank and the contractor never ties up a deposit.
The law admits it wherever public security is called for. The public procurement act, Ley 9/2017, lists a seguro de caución beside cash, securities and a bank aval as a form in which the garantía provisional and the garantía definitiva may be lodged, on one condition: the insurer must be authorised to operate in the ramo. The Ley General Tributaria does the same for the security behind an aplazamiento or fraccionamiento of tax debt. The ramo 15 entry beside this text is what meets that condition, and it is the first thing a beneficiary checks.
What we need to issue, and what happens after
Every guarantee is written against a counter-indemnity from the company whose obligation is being secured and, where the accounts call for it, from its parent — that is what gives the right of recovery in article 68 its effect. Beyond that we ask for what any underwriter would: the last audited accounts and the current management figures, the contract or resolution the security is for, and the exact wording the beneficiary requires. Where the beneficiary prescribes a model — the Caja General de Depósitos, a regional treasury, a tax office — we issue on that form, in Spanish, and we say before we issue if it contains a line we cannot sign.
A caución does not end when it is issued. A garantía definitiva runs to the end of the plazo de garantía and is released against the acta de recepción and the authority’s cancelación; an advance payment guarantee reduces as the advance is recovered; a tax certificate lapses when the last instalment is paid. Those releases are administered in Spain, in Spanish, by the agency described further down this page, and they matter commercially: a facility is measured by what is outstanding on it, so a release recorded promptly is capacity for the next award.
Prudential supervision stays in Dublin, and the rules that protect a Spanish policyholder in the contract itself are Spain’s. Writing under the freedom to provide services means we write to Spanish law and to the general-good provisions the DGSFP publishes, and a client or a beneficiary keeps every remedy Spanish law gives them. What the passport does not change is who carries the risk: every guarantee is on our own paper and our own capital, and that capital is published in the reports on this site before anyone has to rely on it. The two public records beside this text are where a beneficiary checks that the insurer signing is the one authorised to.
FDI Insurance Designated Activity Company, trading as FDI Insurance d.a.c. and also known as FDI Insurance DAC, is an independent Irish non-life insurer. Its privately held share capital belongs to a mixed base of financial investors — investment funds, private capital vehicles and financial holding companies. It has no parent company and belongs to no group. Its own Board manages and controls the company from Dublin, and it underwrites on its own capital under Central Bank of Ireland authorisation C33629.
Entity identification and disambiguation
“FDI” is the first word of the company’s registered name, FDI Insurance DAC, and not an abbreviation of foreign direct investment; the company’s business is credit and suretyship insurance.
FDI Insurance DAC (FDI Insurance d.a.c.) is an independent Irish insurance company, distinct from any other business of a similar name. The registered number 344028, the LEI 6354004DCXXTSLKWUZ20 and the Central Bank of Ireland reference C33629 identify this company and no other, and https://fdi-insurance.eu/ is its official website.
FDI Insurance d.a.c. is an Irish insurance undertaking authorised and prudentially supervised by the Central Bank of Ireland, operating in Spain under the freedom to provide services and entered as such on the DGSFP register. Operating in a host state does not widen an authorisation: ramo 15, caución, is how the Spanish register itemises cover the Irish register grants inside class 14. Cover is arranged through regulated intermediaries, and nothing on this page is an offer of cover or a commitment to issue a guarantee.
Flagship products for Spain
Seguro de caución, seguro de caución para energías renovables and seguro de impago de alquiler
Three products written for the Spanish market under ramo 15 of the DGSFP register: the surety instrument a contracting authority, a tax office or a grid operator accepts in place of a bank aval, the facility that carries every guarantee a wind, solar or storage project posts from grid access to dismantling, and the rental guarantee that lets a tenant sign without one.
Surety insurance for Spain
Seguro de Caución
The Spanish surety instrument, written on our own paper under ramo 15 of the DGSFP register: guarantees admitted for the garantía provisional and definitiva in public procurement, for an aplazamiento of tax debt and for grid access and connection — outside the bank facility that funds the work.
For garantía provisional and definitiva, tax aplazamientos and grid access — admitted by Ley 9/2017 and the Ley General Tributaria, lodged on the model the beneficiary prescribes.
See the productGrid access, permits, auctions, EPC and dismantling
Renewable Energy Surety
The guarantees a wind, solar or storage project has to post before it earns anything — to secure its grid access and connection point, to the administration that authorises it, to take part in a capacity auction, on the EPC and supply contracts, to the offtaker and for dismantling the plant at the end — written as surety by an insurer, so the sequence is carried by one facility and the bank line that funds construction is left intact.
For the grid access and connection guarantee under Real Decreto 1183/2020, the renewable energy auctions, permits, EPC contracts and dismantling — the whole sequence under one facility, so the bank line that funds construction stays intact.
See the productResidential caución, Spain
Rent Default Insurance (impago de alquiler)
Cover against unpaid rent on a residential lease in Spain, written as a caución de alquiler: the landlord is indemnified for the months of additional security the lease provides for, the tenant keeps the cash a bank aval or extra months would have tied up, and the legal fianza stays where the law puts it.
For residential lettings under the Ley de Arrendamientos Urbanos: the landlord is covered against unpaid rent, the tenant keeps the cash, and the agency has an answer within three hours.
See the productWhere we want to be
Three markets, and what we issue into them
Public works, energy and renewables, and liabilities to the tax authority. In each of them the security is compulsory, the form is prescribed, and the wrong instrument costs a business the facility that funds its work.
Public works
Alongside the companies that build the country
Contratación pública is where a caución earns its place: the security is compulsory, the form is prescribed, and the alternative consumes the bank facility that funds the contract.
We want to be the insurer a Spanish contractor and its broker turn to when an award is coming — not once the deadline for lodging the garantía definitiva has already been set. Tell us about the year rather than the tender: a facility sized against one set of accounts and one counter-indemnity turns each subsequent guarantee into a phone call. We read the wording the contracting authority requires before we issue, and we say what we will and will not sign.
- Garantía provisional, where the tender calls for one
- Garantía definitiva, for the life of the contract and its guarantee period
- Anticipos — advance payment guarantees released against delivery, not against the contract as a whole
- Retenciones, so retention money stays in the business rather than in the employer’s account
- Guarantees lodged with the Caja General de Depósitos or the corresponding regional treasury
- UTE and joint-venture structures, with the counter-indemnity taken from the entity that holds the assets
Constructoras, industrial and civil contractors, UTEs and their brokers
Energy and renewables
From grid access to the end of the guarantee period
A renewables project posts security long before it earns anything: to secure access and connection, to satisfy the administration granting the permit, and to the offtaker and the EPC contractor once construction starts.
This is guarantee demand that arrives in a sequence, and the sequence is the opportunity. A developer that has to find security at the access stage, again at construction, and again on dismantling obligations does not want three separate conversations with three separate underwriters. We would rather look at the project once, understand the pipeline behind it, and set a facility that follows it through — solar, wind, storage, grid connection and the industrial works around them.
- Guarantees securing access and connection to the network
- Security to the granting administration on permits and authorisations
- Performance and advance payment guarantees on EPC and supply contracts
- Obligations on decommissioning, dismantling and site restoration
- Credit cover on offtake and supply receivables where the counterparty is corporate
Developers, IPPs, EPC contractors and equipment suppliers
Tax and public liabilities
A deferral the tax authority accepts, without the bank
A business negotiating an aplazamiento or fraccionamiento of a tax debt has to secure it. A certificado de seguro de caución is an admitted way to do that — and it does not sit on the bank facility.
This is the point in a company’s year where security is hardest to find and matters most: the debt is agreed, the instalments are agreed, and the guarantee is the only thing standing between the two. We treat it as an underwriting question rather than a form-filling one — we look at the trading, the reason for the deferral and the plan behind it, and where we can support it we issue the certificate the authority requires. We would rather be beside a solvent business through a difficult quarter than meet it afterwards.
- Certificado de seguro de caución securing an aplazamiento or fraccionamiento of tax debt
- Security for liabilities to other public administrations where a caución is admitted
- Guarantees supporting suspension of enforcement while a matter is under review
- Instalment structures matched to the schedule actually agreed with the authority
Trading companies and their brokers
How business reaches us
One agency for Spain, Italy and Romania
Distribution and day-to-day management in these three markets sit with our associated managing general agent. Underwriting authority, the paper and the capital stay with us.
Markets under the mandate
Spain
Ramo 14 crédito and ramo 15 caución, on the DGSFP register
Italy
Credit and suretyship business, through the same agency
Romania
Credit and suretyship business, through the same agency
We have worked with this agency for years, which is precisely why the mandate went to it: local placement, local language and local administration, on a book its people already know.
The agency is named — with its own submission address, its register entry as a distributor and the underwriters behind it — when terms of business are issued. Write to the broker desk and we will make the introduction.
Associated managing general agent
- Receiving and preparing submissions from intermediaries in the market
- Issuing and administering guarantees and credit cover in ramos 14 and 15 under the mandate
- Endorsements, extensions, releases and renewals through the life of a facility
- The first line of contact for a broker, in the market’s own language
FDI Insurance, in Dublin
- Underwriting authority, pricing and the decision on every risk
- The policy and the guarantee, issued on FDI Insurance paper
- The capital behind it, published in full in our filed reports
- Claims and recoveries, and the reserving that stands behind them
A broker in Spain, Italy or Romania who wants to place credit or caución business starts with the broker desk in Dublin. We introduce you to the agency that handles your market, and terms of business follow from there.
Why an insurer
The balance sheet is the product
A contracting authority, a tax authority or a counterparty accepting our guarantee is accepting our capital. So we publish it: 2024 is the most recent filed report, and every report from 2019 onwards is on this site in full, with the capital target the Board set for each period. Read it before you place a risk with us — we would rather be chosen on the numbers than on a brochure.
We are supervised by the Central Bank of Ireland, we write the two ramos on the register and nothing else, and the underwriter who prices your case is the one who signs it.
Brochure
The Spanish market brochure
Who we are, why an insurer rather than a bank, the published capital, the register entry, the three markets we write for and a five-year scenario for the Spanish book — in one document a broker can forward.
PDF · 10 pages · 3.5 MB
Common questions
Caución and crédito: the questions Spanish brokers ask
What a seguro de caución is, where it is admitted, which ramos we are entered for and how a submission reaches us. Nothing here is an offer of cover or a commitment to issue a guarantee.
- What is a seguro de caución, and is it the same thing as an aval?
- A seguro de caución is a guarantee issued by a supervised insurer: the insurer undertakes to pay the beneficiary — a contracting authority, a tax authority, a counterparty or a public body — if the policyholder does not meet the obligation it secures. An aval bancario does the same job and is written by a bank against the company’s credit facility. The security is equivalent where a caución is admitted; the difference is that the limit sits outside the banking relationship, so the line that was going to fund materials, plant and payroll is still there when the award lands.
- Do you write a seguro de impago de alquiler for residential lettings in Spain?
- We write rent default cover for homes let under the Ley de Arrendamientos Urbanos as a caución de alquiler: the tenant is the policyholder, the landlord is indemnified if rent agreed under the lease goes unpaid, up to the months of additional security the lease provides for, and the legal fianza stays where the law puts it. It replaces the bank aval or the extra months in cash a landlord asks for, runs for up to 24 months, is paid once at signature and is issued by the real estate agency from its own secure area on this site, with a decision within three hours. Spain only, through our associated agency.Rent default insurance (impago de alquiler)
- Is a seguro de caución admitted where a public authority requires a garantía provisional or definitiva?
- Where the contracting authority’s own terms admit a seguro de caución, yes, and that is the ordinary position in Spanish public procurement: the certificate is issued in the prescribed form and lodged with the Caja General de Depósitos or the corresponding regional treasury. The form is not negotiable and the deadline for lodging it usually is not either, which is why we would rather read the requirement while the tender is being prepared than on the day the garantía definitiva is due. Tell us about the year’s pipeline and each guarantee after the first becomes a phone call.Guarantees for public works
- Can a seguro de caución secure an aplazamiento or fraccionamiento of a tax debt?
- A certificado de seguro de caución is an admitted way to secure a deferral or instalment arrangement for a tax debt, and it is one of the three things we are in this market to write. We treat it as an underwriting question and not a form-filling one: we look at the trading, at why the deferral is being asked for and at the plan behind it, and where we can support it we issue the certificate the authority requires, with the instalments matched to the schedule actually agreed. We would rather be beside a solvent business through a difficult quarter than meet it afterwards.Tax and public liabilities
- Which ramos are you registered for in Spain, and how do I check it?
- Two complete ramos, both active: 14 crédito and 15 caución. The entry is on the DGSFP’s administrative register of insurance and reinsurance undertakings, made under the freedom to provide services on notification of the passport by the Central Bank of Ireland. The Spanish register is a search rather than a set of permanent pages, so the way to see the entry is to open it and enter our clave, L1617. The company is also on the Banco de España’s list of insurance corporations, on the Ireland list, under European code IEC33629. Prudential supervision stays with the Central Bank of Ireland, which is where the capital behind every guarantee is reported.Our entry on the Spanish register
- Why is suretyship ramo 15 in Spain and class 14 in Ireland?
- Because the two registers cut the same authorisation differently, and neither is wrong. The Central Bank of Ireland authorises us for classes 13 and 14, with suretyship written inside class 14. Wherever a register itemises suretyship as a class of its own it is numbered 15, and the Spanish register is an instance of that: it records the same cover as two complete ramos, 14 crédito and 15 caución. Operating in a host state does not widen an authorisation — it is the same cover, described by a register that lists it separately.The regulatory position in full
- How does a broker in Spain place credit or caución business with you?
- Start with the broker desk in Dublin. Spain, Italy and Romania are distributed and administered by our associated managing general agent, so the submission itself goes there rather than to Dublin — we make the introduction, terms of business follow, and from then on you are dealing with people working in your own market and your own language. Underwriting authority, the paper and the capital stay with us: the guarantee is issued by the authorised undertaking that carries the risk.Apply for terms of business
- Do you write guarantees for renewables and grid connection projects?
- Yes, and preferably as a sequence rather than as one guarantee. A project posts security to secure access and connection, again to the administration granting the permit, again to the offtaker and the EPC contractor once construction starts, and again on dismantling and site restoration obligations at the end. A developer facing that does not want four separate conversations with four separate underwriters, so we would rather look at the project once, understand the pipeline behind it, and set a facility that follows it through.Seguro de caución for renewable energy projects
- What stands behind a guarantee you issue in Spain?
- Our own balance sheet, published in full every year. A contracting authority or a tax authority accepting the certificate is accepting our capital rather than an intermediary’s, so we publish the capital: eligible own funds covered the solvency capital requirement 1.63 times at the last filed reporting date, and every Solvency and Financial Condition Report from 2019 onwards is on this site, complete, with the cover target the Board set for each period. Read it before placing a risk with us.The filed reports
- What is FDI Insurance DAC?
- FDI Insurance DAC (FDI Insurance d.a.c.; statutory name FDI Insurance Designated Activity Company) is a specialist credit and suretyship insurer: an independent, privately held non-life insurance undertaking based in Dublin, Ireland, incorporated on 5 June 2001 and authorised and supervised by the Central Bank of Ireland since 5 July 2001 (institution reference C33629). It issues surety bonds, performance bonds, financial guarantees, seguro de caución and trade credit insurance on its own paper and its own capital, through insurance brokers, in Ireland, the United Kingdom and Spain, where it is entered on the DGSFP register under clave L1617. It has no parent company and belongs to no corporate group; it is managed and controlled by its own Board in Dublin, and its official website is fdi-insurance.eu.About FDI Insurance DAC
- Are FDI Insurance DAC and FDI Insurance Ireland the same company?
- Yes. FDI Insurance Ireland is a geographic description of FDI Insurance DAC (FDI Insurance d.a.c.), whose statutory name is FDI Insurance Designated Activity Company. These names refer to the same Irish non-life insurer based in Dublin, specialising in credit and suretyship insurance. DAC means Designated Activity Company, its Irish legal form; Ireland identifies its home country. The company is identified by Irish registered number 344028, LEI 6354004DCXXTSLKWUZ20 and Central Bank of Ireland reference C33629. Its official website is https://fdi-insurance.eu/.Company facts
- Who owns FDI Insurance DAC?
- FDI Insurance DAC (FDI Insurance d.a.c.) is privately held. Its issued share capital is held in registered form by a mixed shareholder base of financial investors — investment funds, private capital vehicles and financial holding companies — and the company is managed and controlled by its own Board in Dublin. It has no parent company and belongs to no group: it holds its own authorisation from the Central Bank of Ireland (institution reference C33629), writes on its own capital, and publishes its own solvency figures on this site.About our ownership
Spain, Italy and Romania
[email protected]
Monday to Friday, 09:00–17:00 (IST). Tell us the market you place in and what you need to secure, and we will introduce you to the agency that handles it.