Guarantees & surety
Rent Default Insurance (impago de alquiler)
Cover against unpaid rent on a residential lease in Spain, written as a caución de alquiler: the landlord is indemnified for the months of additional security the lease provides for, the tenant keeps the cash a bank aval or extra months would have tied up, and the legal fianza stays where the law puts it.
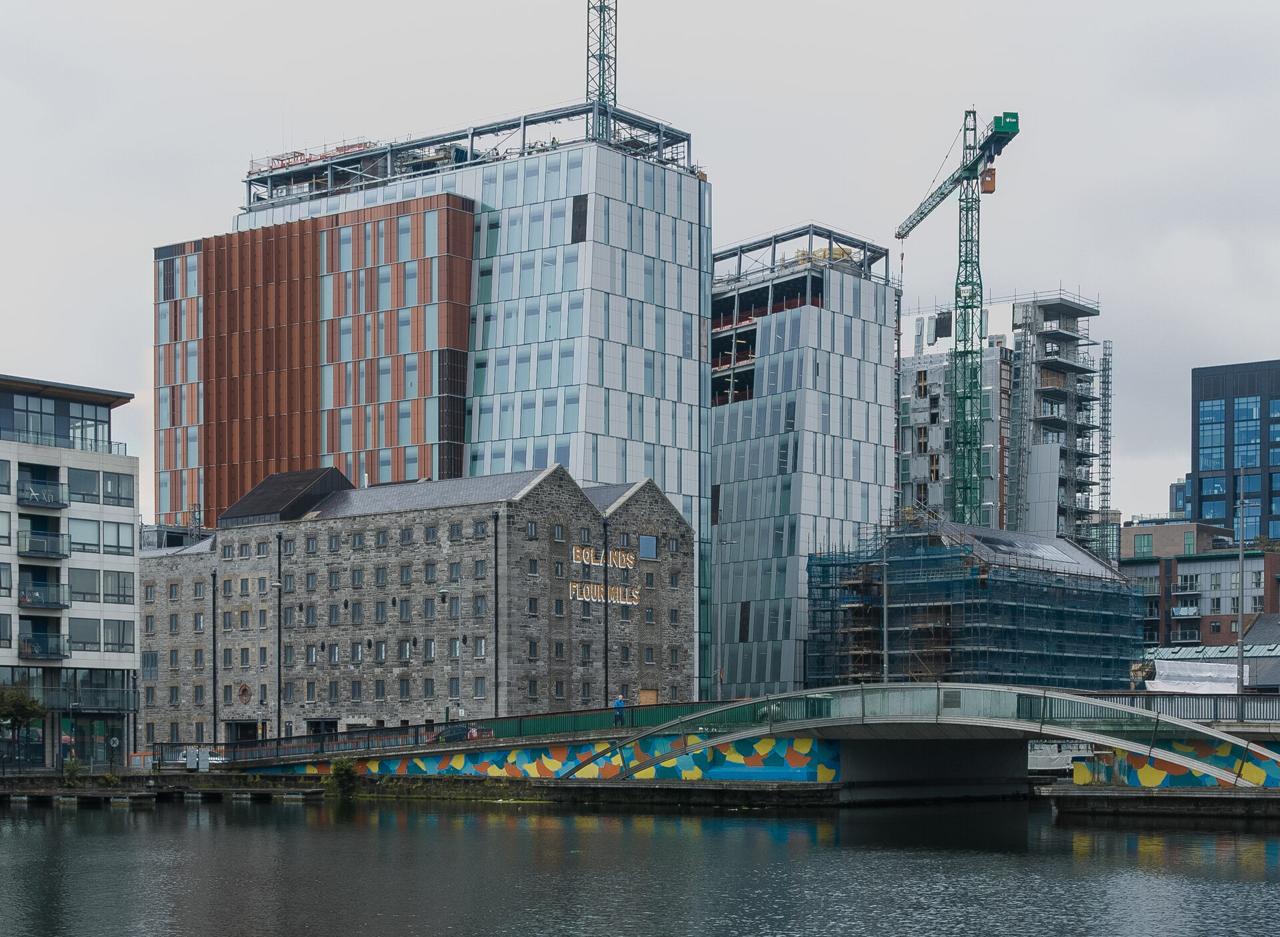
Boland’s Quay, Dublin · William Murphy, CC BY-SA 2.0
Who it is for
Real estate agencies and landlords letting homes in Spain under the Ley de Arrendamientos Urbanos, and brokers with a network of agencies
What it does
- Pays the landlord the rent agreed under the lease that goes unpaid, up to the months the policy states
- Replaces the bank aval or the extra months in cash a landlord asks for on top of the legal fianza
- Runs for up to 24 months, where most rental guarantees on the Spanish market stop at twelve
- Priced for a household and paid once at signature, so the tenant keeps the deposit money
- Quoted in real time by the agency and answered within three hours, with an underwriter reading the cases the scoring is unsure of
- Signed by the tenant with a one-time code; the certificate reaches the landlord the same day
The product in full
Every residential letting in Spain starts with the fianza the Ley de Arrendamientos Urbanos requires: one month’s rent, paid in cash and lodged with the regional housing body for the life of the contract. What decides who gets the flat is the security a landlord asks for on top of it — a bank aval, or up to two further months in cash — and that requirement turns away tenants who can plainly pay the rent but cannot produce the cash, the permanent contract or the Spanish payslips the aval needs.
Our rent default cover is written as a caución de alquiler, a seguro de caución in the sense of article 68 of the Ley de Contrato de Seguro. The tenant is the tomador; the landlord is the asegurado. If rent agreed under the lease goes unpaid, the landlord is indemnified up to the months the policy states — the same months the additional security would have covered — and what we pay is owed back to us by the tenant. The landlord holds a supervised insurer’s undertaking instead of a bank’s or a relative’s, the tenant keeps the cash, and the legal fianza stays exactly where the law puts it.
It is searched for as a seguro de impago de alquiler, and it answers the same need — rent that is not paid — from the other side of the lease. The policy landlords already know is bought by the landlord, covers a year or more of defaults and legal costs, and is priced on the landlord’s whole portfolio. Ours is bought for the tenant, covers the agreed security and nothing more, and is priced on the tenant: deliberately low, paid once at signature, for up to 24 months where most of the market stops at twelve. An eviction for non-payment in Spain can take many months, sometimes more than a year, and a guarantee that expires in the middle of it protects nobody.
How it works
What happens, in order
From the first enquiry to the point the cover, the contract or the facility is in place.
The agency enters the lease
An agency that has joined the programme signs in to its own secure area on this site and enters the rent, the term, the months of additional security the landlord wants and the tenant’s details. The premium is quoted on screen in real time as the figures go in.
Scoring, and an underwriter where it is unsure
An automatic scoring model built for residential tenants reads the tenant’s income, its stability and the payment history the tenant has consented to share, and returns a decision within three hours at most. Where the model is unsure an underwriter reads the file inside the same window. Nationality, employer and length of residence in Spain are not conditions.
The tenant signs with a one-time code
The agent pre-approves the policy on screen, the tenant receives it by email and signs it with a one-time code sent to their phone, and the certificate reaches the landlord the same day. Nothing is posted and nobody visits a bank.
It follows the lease
One tenant or several co-tenants on one contract, a term of six months or two years. The policy is renewed when the lease is extended and released when the lease ends early; if rent goes unpaid, the landlord claims up to the months the policy states.
Suitability
Where the Rent Default Insurance (impago de alquiler) fits
The cases it answers, the cases it does not, and what an underwriter needs before quoting.
It is the right answer when
- A landlord asks for a bank aval or extra months in cash on top of the legal fianza, and the tenant has the income for the rent but not the cash or the paperwork.
- A real estate agency wants an answer before the applicant walks out and signs somewhere else.
- A broker brings an agreement with a chain or network of agencies and wants the programme to run through it.
Look at something else when
- The legal fianza itself: that remains a cash deposit lodged with the regional housing body, and nothing here replaces it.
- A landlord who wants cover for a year or more of defaults and legal costs across a portfolio — that is the landlord’s own seguro de impago, and the two can coexist on one lease.
- A letting outside Spain, or a commercial lease, for which the rent deposit guarantee is the product.
What we need to quote
- 1.The lease: rent, term, and the months of additional security the landlord requires.
- 2.The tenant’s details and consent to share income and payment history for scoring.
- 3.For an agency joining the programme: the city, the volume of leases signed in a year and the guarantee landlords currently require.
Questions
What brokers ask us about this product
Is this a seguro de impago de alquiler?
It covers the same event — rent that is not paid — but it is written as a caución for the tenant rather than as a policy the landlord buys on its portfolio. The landlord is indemnified up to the agreed months of security; what the caución replaces is the aval and the extra months in cash, which is what the tenant could not produce.
How long does the cover run?
Up to 24 months, renewed when the lease is extended and released when it ends early. Most rental guarantees on the Spanish market stop at twelve, which is shorter than many evictions for non-payment take to run their course.
Who can offer it?
Real estate agencies established in Spain, once they have joined the programme through our associated agency for the Spanish market, and brokers who bring an agreement with a chain of agencies. There is no volume commitment, no fee to join and no exclusivity. The enquiry form is the way in.
The programme
How the caución de alquiler works, and how an agency joins
The insight sets out the law — the fianza, what a landlord may ask on top, where the caución sits — and the newsroom item is the invitation to real estate agencies, with the portal, the scoring and the one-time-code signature described in full.
The programme is for Spain only, for residential leases under the Ley de Arrendamientos Urbanos, in Spanish, distributed and administered through our associated managing general agent. Every certificate is issued on FDI Insurance paper under our DGSFP entry for ramo 15, caución, against the balance sheet published in the solvency section of this site.
Request information
Ask us about the Rent Default Insurance (impago de alquiler)
The form reaches an underwriter in Dublin. If you are an intermediary, say so and we will route it to the broker desk.