Financement immobilier
Lifestyle Select Options
Le déblocage le plus élevé de la gamme : la souscription tient compte de la santé et du mode de vie, de sorte qu'un client en moins bonne santé peut emprunter davantage sur le même bien.
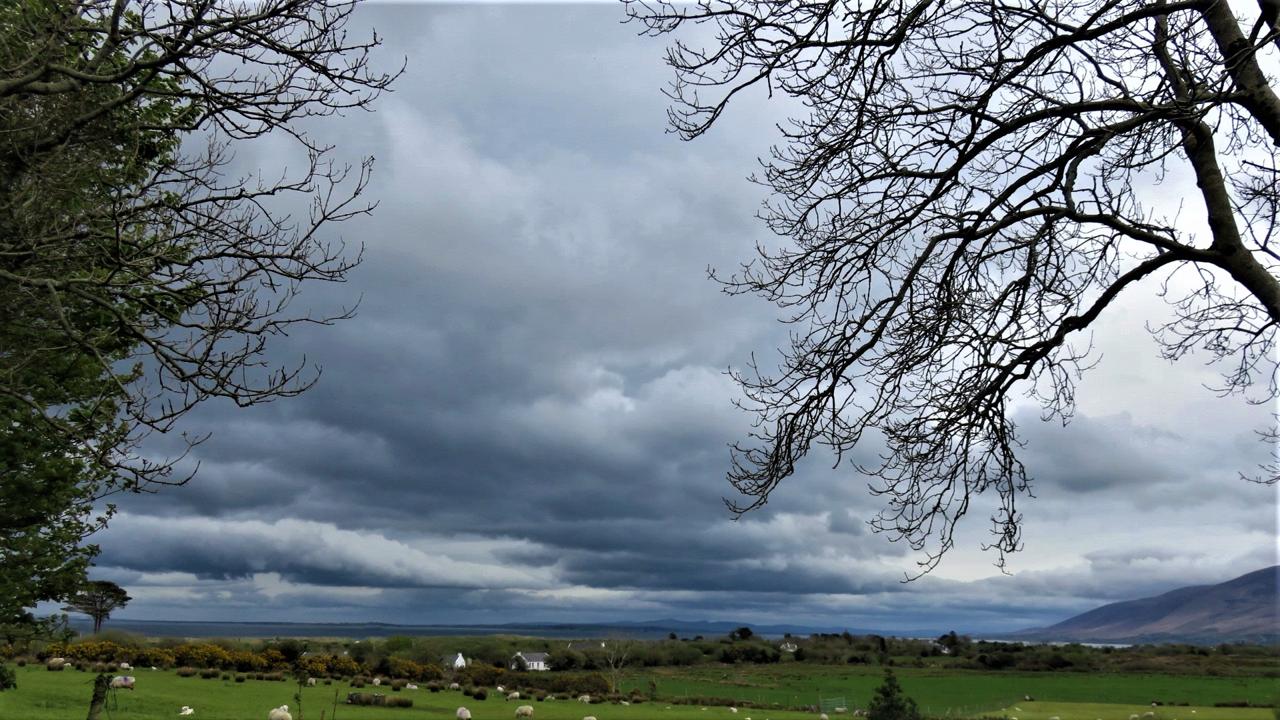
Péninsule de Dingle, comté de Kerry · Maoileann, CC BY-SA 4.0
À qui il s'adresse
Clients dont l'état de santé ou le mode de vie justifie des conditions majorées
Ce qu'il fait
- Sélection médicale pour une quotité de financement plus élevée
- Questionnaire de santé et de mode de vie à la souscription
- Structure en capital ou en tirages
- La garantie d'absence de dette résiduelle est maintenue
Le produit en détail
Lifetime mortgage lending is limited by how long the loan is expected to run, because the longer it runs the more the rolled-up interest grows against a property value that may not keep pace. So a lender that knows a loan is likely to be shorter can lend more against the same house.
That is what this product does. A health and lifestyle questionnaire is completed at application, and where the answers indicate a shorter expected term, the loan-to-value available rises — up to 53% on enhanced terms, against up to 41% on the standard product. On a £350,000 property that is a difference of about £42,000.
It is worth being direct about what is happening, because clients notice: this is the same underwriting logic as an enhanced annuity, and it points the same way. A client in poorer health is offered more, not less. Nothing about the protections changes — the no negative equity guarantee is retained in full, and the loan can be structured as a lump sum or as a drawdown facility.
The questionnaire is therefore worth completing carefully rather than quickly. A client who understates a condition out of habit or pride reduces the amount available to them, and it is one of the few forms in financial services where that is true.
Documentation
La documentation produit est remise aux intermédiaires accrédités. Demandez-la à votre souscripteur, ou demandez-la via le formulaire de demande.
- Illustration des données clésSur demande
- Questionnaire de santé et de mode de vieSur demande
Comment cela fonctionne
Ce qui se passe, dans l'ordre
De la première demande jusqu'à la mise en place de la garantie, du contrat ou de la ligne.
The broker identifies that enhanced terms may apply
Where health or lifestyle factors are present. Minimum age 55.
The health and lifestyle questionnaire is completed
At application. It establishes whether an enhanced loan to value is available and by how much.
The property is valued and terms issued
Up to 53% loan to value on enhanced terms, with a Key Facts Illustration.
A lump sum or drawdown structure is chosen
Both are available. A drawdown structure keeps the undrawn part free of interest, as on Capital Select Options.
Interest rolls up and the loan is repaid on death or care
With the no negative equity guarantee retained in full.
Les chiffres
Un exemple chiffré
Des calculs donnés à titre indicatif, pour que la structure du produit se voie plutôt qu'elle se décrive. Rien ici n'est une offre ni une projection.
A £350,000 property, standard against enhanced terms
A client of 68 whose questionnaire supports enhanced terms. Illustrative loan-to-value figures.
- Property value
- £350,000
- Standard loan to value at this age
- 41%
- Available on standard terms
- £143,500
- Enhanced loan to value
- 53%
- Available on enhanced terms
- £185,500
- Additional release
- £42,000
- No negative equity guarantee
- Retained
- Structure
- Lump sum or drawdown
Illustrative. The enhanced loan to value depends entirely on the questionnaire and the underwriting outcome for the actual client, and 53% is the maximum available on the product rather than a figure any particular applicant will reach.
What enhanced underwriting releases
Available on the illustrative £350,000 property above.
Voir ces chiffres sous forme de tableau
| Valeur | |
|---|---|
| Standard terms, 41% | £143.5k |
| Enhanced terms, 53% — Same property, same age | £185.5k |
Adéquation
Où Lifestyle Select Options trouve sa place
Les cas auxquels il répond, ceux auxquels il ne répond pas, et ce qu'un souscripteur demande avant de tarifer.
C'est la bonne réponse lorsque
- Clients whose health or lifestyle would support a shorter expected term.
- Cases where the standard loan to value falls short of what the client needs.
- Clients who want the higher release with the guarantees unchanged.
Il faut regarder ailleurs lorsque
- A client in good health with no lifestyle factors — the questionnaire will not improve their terms and Advantage Options is likely cheaper.
- Anyone unwilling to complete health underwriting.
Ce qu'il nous faut pour tarifer
- 1.The broker’s suitability assessment and the clients’ ages.
- 2.The completed health and lifestyle questionnaire.
- 3.Property details and value, and the amount required.
Questions
Ce que les courtiers nous demandent sur ce produit
Why does poorer health increase the amount available?
Because the loan is expected to run for less time, so less interest is expected to roll up against the property. It is the same logic as an enhanced annuity.
Is the no negative equity guarantee weakened on enhanced terms?
No. It is retained in full. The higher loan to value is the only thing that changes.
Will 53% always be available?
No — it is the product maximum. The actual figure comes from the questionnaire and the client’s age, and most enhanced cases land below it.
Financement immobilier
Autres produits de cette gamme
Demander des informations
Interrogez-nous sur Lifestyle Select Options
Le formulaire parvient à un souscripteur à Dublin. Si vous êtes intermédiaire, dites-le et nous l'orienterons vers le bureau courtiers.