Financiación de vivienda
Lifestyle Select Options
La mayor disposición de la gama: emplea suscripción médica y de hábitos de vida para que los clientes con peor estado de salud puedan obtener más sobre el mismo inmueble.
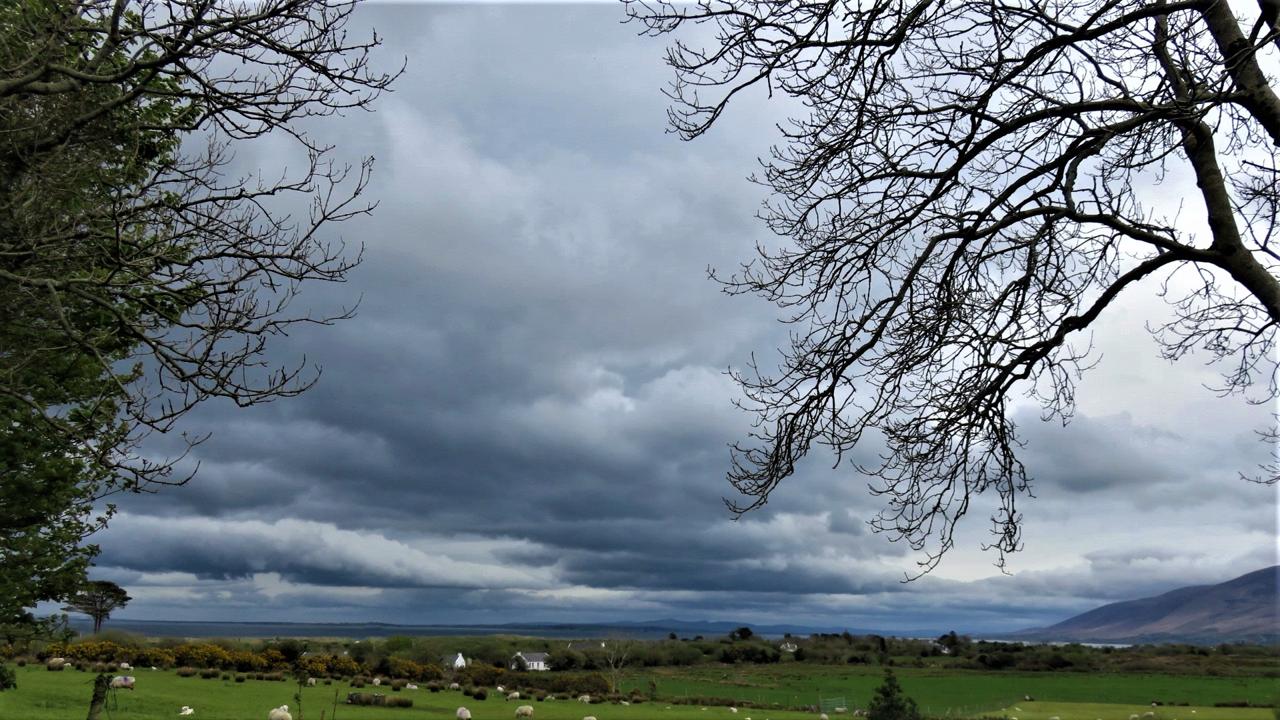
Península de Dingle, Co. Kerry · Maoileann, CC BY-SA 4.0
Para quién es
Clientes cuya salud o estilo de vida permite condiciones mejoradas
Qué hace
- Con selección médica para una relación préstamo-valor más alta
- Cuestionario de salud y estilo de vida en la solicitud
- Estructura de capital único o de disposiciones
- Se mantiene la garantía de no patrimonio negativo
El producto en detalle
Lifetime mortgage lending is limited by how long the loan is expected to run, because the longer it runs the more the rolled-up interest grows against a property value that may not keep pace. So a lender that knows a loan is likely to be shorter can lend more against the same house.
That is what this product does. A health and lifestyle questionnaire is completed at application, and where the answers indicate a shorter expected term, the loan-to-value available rises — up to 53% on enhanced terms, against up to 41% on the standard product. On a £350,000 property that is a difference of about £42,000.
It is worth being direct about what is happening, because clients notice: this is the same underwriting logic as an enhanced annuity, and it points the same way. A client in poorer health is offered more, not less. Nothing about the protections changes — the no negative equity guarantee is retained in full, and the loan can be structured as a lump sum or as a drawdown facility.
The questionnaire is therefore worth completing carefully rather than quickly. A client who understates a condition out of habit or pride reduces the amount available to them, and it is one of the few forms in financial services where that is true.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Ilustración de datos claveA petición
- Cuestionario de salud y estilo de vidaA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
The broker identifies that enhanced terms may apply
Where health or lifestyle factors are present. Minimum age 55.
The health and lifestyle questionnaire is completed
At application. It establishes whether an enhanced loan to value is available and by how much.
The property is valued and terms issued
Up to 53% loan to value on enhanced terms, with a Key Facts Illustration.
A lump sum or drawdown structure is chosen
Both are available. A drawdown structure keeps the undrawn part free of interest, as on Capital Select Options.
Interest rolls up and the loan is repaid on death or care
With the no negative equity guarantee retained in full.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
A £350,000 property, standard against enhanced terms
A client of 68 whose questionnaire supports enhanced terms. Illustrative loan-to-value figures.
- Property value
- £350,000
- Standard loan to value at this age
- 41%
- Available on standard terms
- £143,500
- Enhanced loan to value
- 53%
- Available on enhanced terms
- £185,500
- Additional release
- £42,000
- No negative equity guarantee
- Retained
- Estructura
- Lump sum or drawdown
Illustrative. The enhanced loan to value depends entirely on the questionnaire and the underwriting outcome for the actual client, and 53% is the maximum available on the product rather than a figure any particular applicant will reach.
What enhanced underwriting releases
Available on the illustrative £350,000 property above.
Ver estas cifras en una tabla
| Valor | |
|---|---|
| Standard terms, 41% | £143.5k |
| Enhanced terms, 53% — Same property, same age | £185.5k |
Idoneidad
Dónde encaja Lifestyle Select Options
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- Clients whose health or lifestyle would support a shorter expected term.
- Cases where the standard loan to value falls short of what the client needs.
- Clients who want the higher release with the guarantees unchanged.
Conviene mirar otra cosa cuando
- A client in good health with no lifestyle factors — the questionnaire will not improve their terms and Advantage Options is likely cheaper.
- Anyone unwilling to complete health underwriting.
Lo que necesitamos para tarificar
- 1.The broker’s suitability assessment and the clients’ ages.
- 2.The completed health and lifestyle questionnaire.
- 3.Property details and value, and the amount required.
Preguntas
Lo que los corredores nos preguntan sobre este producto
Why does poorer health increase the amount available?
Because the loan is expected to run for less time, so less interest is expected to roll up against the property. It is the same logic as an enhanced annuity.
Is the no negative equity guarantee weakened on enhanced terms?
No. It is retained in full. The higher loan to value is the only thing that changes.
Will 53% always be available?
No — it is the product maximum. The actual figure comes from the questionnaire and the client’s age, and most enhanced cases land below it.
Solicitar información
Consúltenos sobre Lifestyle Select Options
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.