Financiación de vivienda
Capital Select Options
Una hipoteca inversa con disposiciones: una línea aprobada de la que el cliente retira efectivo solo cuando lo necesita, de modo que los intereses se devengan únicamente sobre lo dispuesto.
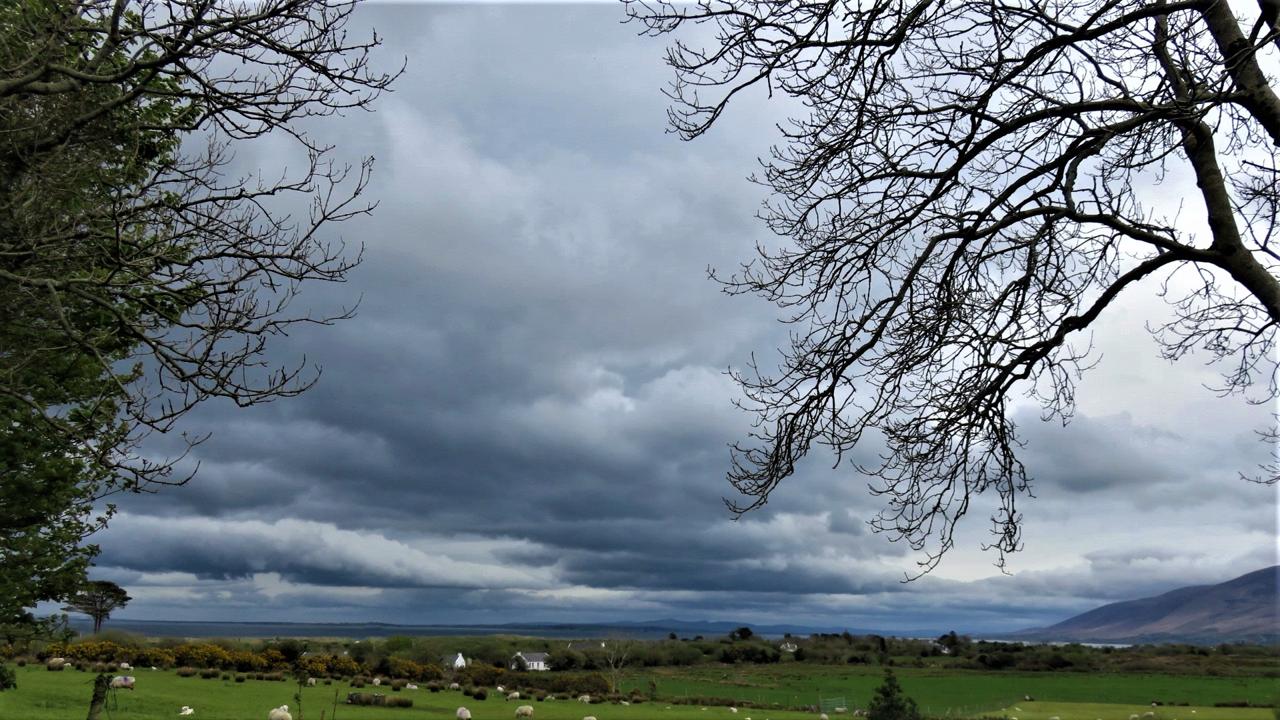
Península de Dingle, Co. Kerry · Maoileann, CC BY-SA 4.0
Para quién es
Clientes que necesitan capital por etapas y no de una sola vez
Qué hace
- Línea de reserva sin coste sobre los fondos no dispuestos
- Disposición mínima de 2.000 £
- Tipo fijo establecido en cada disposición
- Protección de la herencia y protección por cambio a vivienda más pequeña disponibles
El producto en detalle
The most expensive mistake in equity release is borrowing money before it is needed. A client who takes £120,000 as a lump sum and spends £40,000 of it over the first decade has paid rolled-up interest for ten years on £80,000 that sat in a bank account.
Capital Select Options is built to prevent exactly that. An approved facility is agreed at outset, the client draws an initial advance from it, and the rest sits in reserve. Nothing is charged on undrawn funds — no facility fee, no interest, nothing. When more is needed, the client draws from £2,000 upwards and interest starts on that amount from that date.
Each drawdown is at the fixed rate applying when it is taken, which cuts both ways: a client drawing in a lower rate environment benefits, and one drawing in a higher one does not. The reserve is valid for fifteen years, which is long enough for the arrangement to serve as a standing facility rather than a series of applications.
The comparison with a lump sum is the whole argument, and it is arithmetic rather than opinion — the worked example below sets the two side by side on identical assumptions.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Ilustración de datos claveA petición
- Formulario de solicitud de disposiciónA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
A facility is approved
The total the client could borrow, based on age and property value. Nothing is charged on the part not drawn.
An initial advance is taken
From £10,000. Interest begins on this amount only.
Further drawdowns as needed, from £2,000
On the drawdown request form. Each is at the fixed rate applying on the date it is taken.
Interest rolls up on drawn funds only
Each tranche compounds from its own date, not from the date the facility was approved.
Repayment on death or long-term care
From the property sale, with the no negative equity guarantee and the same inheritance and downsizing protections available.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
The same money, drawn in stages against taken at once
A £120,000 facility, £80,000 actually needed over ten years, at an illustrative 6.5%. Both columns use identical assumptions — the only difference is when the money was taken.
- Facility approved
- £120,000
- Initial advance at outset
- £40,000
- Drawdown at year 5
- £20,000
- Drawdown at year 10
- £20,000
- Total drawn
- £80,000
- Balance at year 15, drawn in stages
- £167,819
- Balance at year 15, had £80,000 been taken at outset
- £205,747
- DifferenceInterest never charged, on money not yet needed
- £37,928
- Charged on the £40,000 never drawn
- Nothing
Illustrative at a constant 6.5%. In practice each drawdown is at the rate applying on its own date, so the real comparison depends on where rates go — but the principle that undrawn money costs nothing does not depend on the rate at all.
Balance at year 15, staged against lump sum
The illustrative arrangement above, on identical assumptions.
Ver estas cifras en una tabla
| Valor | |
|---|---|
| Drawn in three stages | £168k |
| Taken as one lump sum — The same £80,000, taken at outset | £206k |
Idoneidad
Dónde encaja Capital Select Options
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- Clients who need capital in stages — home adaptations, care costs, periodic support to family.
- Anyone who would otherwise hold released cash in a bank account.
- Clients who want a standing facility available for fifteen years without reapplying.
Conviene mirar otra cosa cuando
- A client who needs the whole sum at once — Advantage Options prices a lump sum more keenly.
- A client whose health supports a materially higher release — Lifestyle Select Options is the underwritten route.
Lo que necesitamos para tarificar
- 1.The broker’s suitability assessment and the clients’ ages.
- 2.Property details and value.
- 3.The initial advance required, and an indication of the total facility wanted.
Preguntas
Lo que los corredores nos preguntan sobre este producto
Is anything charged on the reserve?
No. Undrawn funds carry no interest and no facility charge. That is the whole design.
What rate applies to a later drawdown?
The fixed rate applying on the date of that drawdown, which may be higher or lower than the initial advance rate. Each tranche then keeps its own rate for life.
What happens after fifteen years?
The reserve validity is fifteen years. A client who expects to need funds beyond that should discuss it with their broker at outset rather than discovering it later.
Solicitar información
Consúltenos sobre Capital Select Options
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.