Financiación de vivienda
Second Home Options
Una hipoteca inversa garantizada sobre una segunda residencia o vivienda vacacional en lugar de la habitual, para propietarios que quieren liberar valor sin tocar la vivienda familiar.
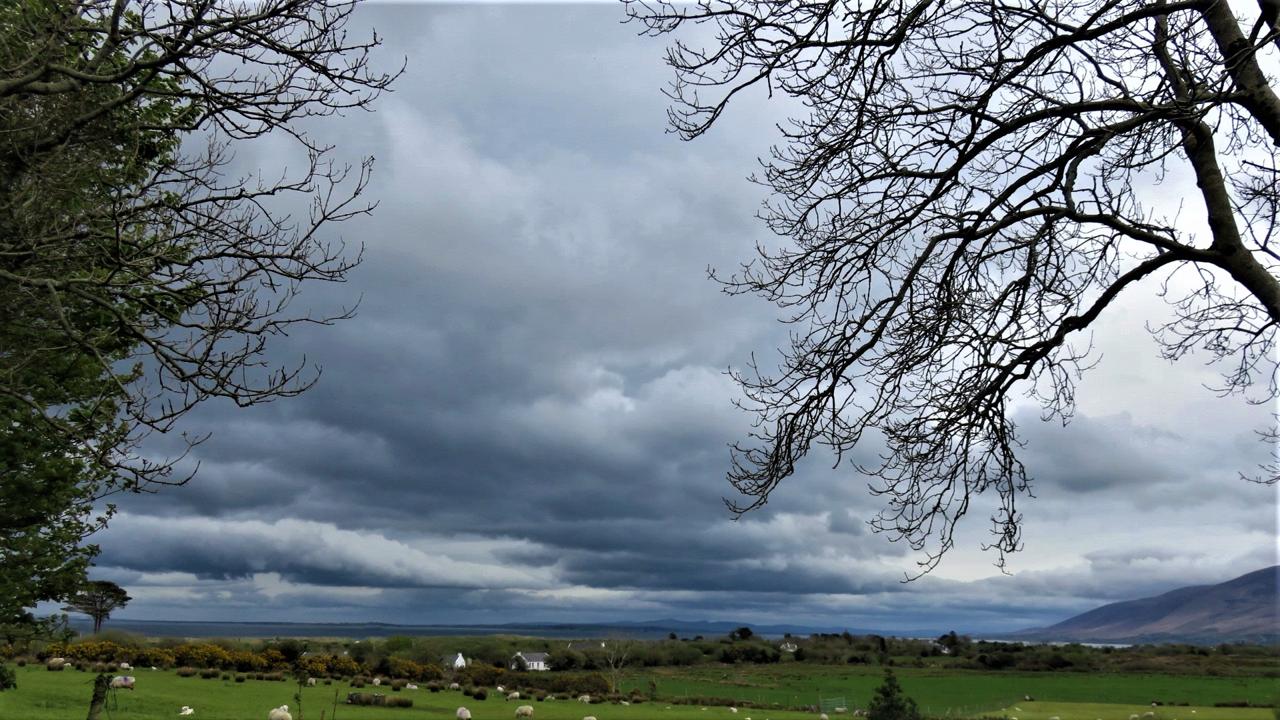
Península de Dingle, Co. Kerry · Maoileann, CC BY-SA 4.0
Para quién es
Propietarios de una segunda residencia o vivienda vacacional
Qué hace
- Garantizado sobre una segunda vivienda, no sobre la residencia habitual
- El inmueble no puede estar arrendado con un contrato de arrendamiento protegido
- Tipo fijo de por vida con garantía de no patrimonio negativo
- Se exige ocupación personal durante parte del año
El producto en detalle
Some clients have equity they would like to use and no wish to touch the family home to reach it. A holiday cottage in Kerry, a flat kept from an earlier life, a property bought for retirement and not yet lived in — all of it is value, and none of it is the main residence.
Second Home Options is a lifetime mortgage secured on that property instead. The mechanics are the same as the rest of the range: no monthly payment, a rate fixed for life, interest rolled up, and a no negative equity guarantee. The differences are in the eligibility criteria, and they exist because a property the owner does not live in full time is a different security.
Two conditions matter most. The property must not be let on an assured tenancy — a lifetime mortgage cannot sit behind a tenant with security of tenure — and the owner must personally occupy it for part of the year. Holiday letting is possible by agreement, and it is worth raising at application rather than after completion.
The loan-to-value is lower than on a main residence, up to 34%, and the minimum property value is higher at £150,000. Both reflect the same thing: a second home is a less certain security and is priced accordingly.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Ilustración de datos claveA petición
- Nota sobre la elegibilidad del inmuebleA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
Eligibility of the property is checked first
Against the property eligibility note: tenure, no assured tenancy, personal occupation for part of the year, minimum value £150,000.
Any letting arrangement is disclosed
Holiday letting is possible by agreement. An assured tenancy is not, and it is better established now than at completion.
The property is valued and terms issued
Up to 34% loan to value, with a Key Facts Illustration.
The loan completes with the rate fixed for life
No monthly payment, interest rolled up, no negative equity guarantee.
Repayment on death or long-term care
From the sale of the second property. The main residence is not security for this loan.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
A £400,000 holiday home, with the main residence untouched
Illustrative figures for a client of 70 releasing against a second property.
- Second property value
- £400,000
- Main residence valueNot security for this loan, and not affected by it
- £520,000
- Maximum loan to value
- 34%
- Released
- £136,000
- Illustrative fixed rate
- 6.9% a year, rolled up
- Balance after 15 years
- £368,000
- Arrendamiento
- Holiday letting only, by agreement
- Personal occupation
- Required for part of the year
Illustrative and not a quotation. The 34% figure is the product maximum and the actual loan to value depends on the youngest borrower’s age. A Key Facts Illustration carries the real rate, charges and projected balances.
Which property is security, and which is not
The illustrative case above.
Ver estas cifras en una tabla
| Released against the property | Equity retained | |
|---|---|---|
| Second home — Security for the loan | £136k | £264k |
| Main residence — Untouched | £0k | £520k |
Idoneidad
Dónde encaja Second Home Options
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- Owners of a second or holiday property who do not want to borrow against the main residence.
- Properties worth £150,000 or more, personally occupied for part of the year.
- Clients whose second property is either unlet or holiday let by agreement.
Conviene mirar otra cosa cuando
- Property let on an assured tenancy — that is the Over 55 Buy-to-Let Option.
- A main residence, which the rest of the range covers at a higher loan to value.
- A property the client never personally occupies.
Lo que necesitamos para tarificar
- 1.The broker’s suitability assessment and the clients’ ages.
- 2.Details and tenure of the second property, and its estimated value.
- 3.Any letting arrangement, and confirmation of personal occupation.
Preguntas
Lo que los corredores nos preguntan sobre este producto
Can the property be let?
Holiday letting is possible by agreement. An assured tenancy is not compatible with this product, and disclosing an existing one early avoids a declined application at valuation.
Why is the loan to value lower than on a main residence?
Because a property the owner does not live in full time is a less certain security, in condition, in occupancy and in resale. The lower loan to value is how that is reflected.
Is the main residence at risk?
No. The loan is secured on the second property only.
Solicitar información
Consúltenos sobre Second Home Options
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.