Financement immobilier
Advantage Options
Un prêt viager hypothécaire à taux fixe plus bas en échange d'une fenêtre de remboursement anticipé plus courte et d'une quotité de financement plus stricte, pour les propriétaires certains que la solution est définitive.
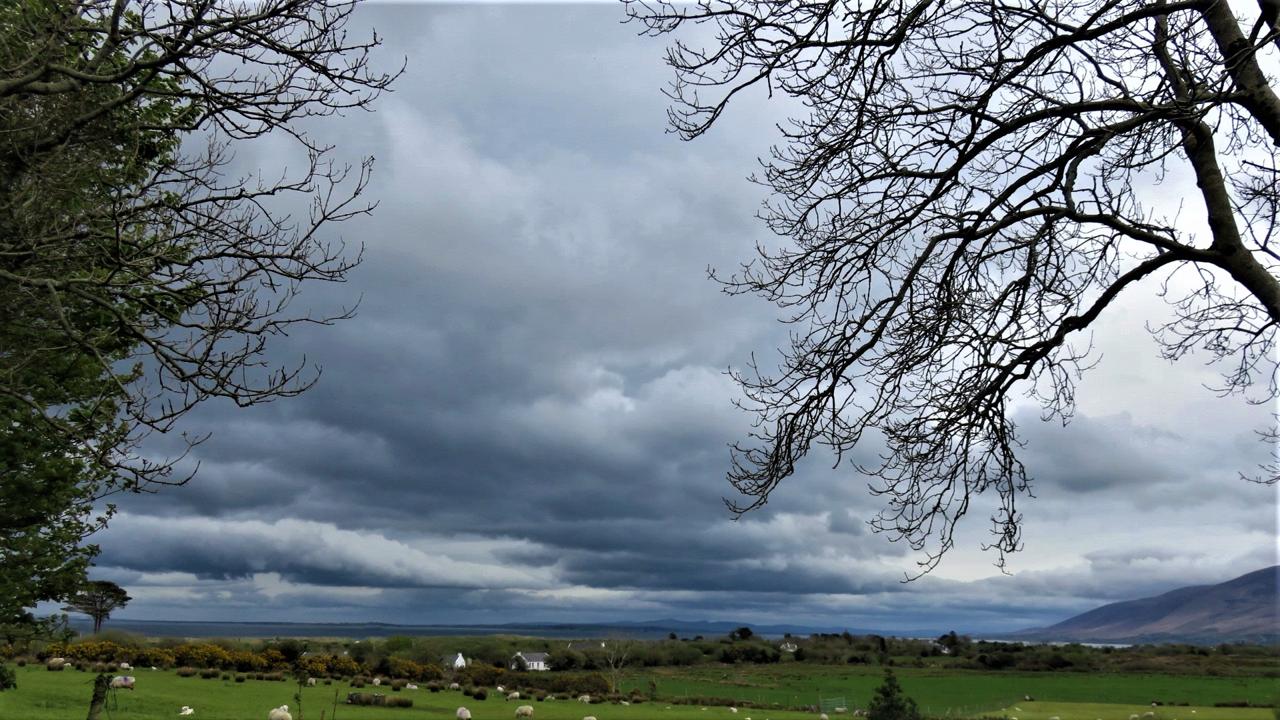
Péninsule de Dingle, comté de Kerry · Maoileann, CC BY-SA 4.0
À qui il s'adresse
Clients seniors réalisant un rachat de valeur immobilière par l'intermédiaire d'un courtier
Ce qu'il fait
- Taux fixe à vie avec garantie d'absence de dette résiduelle
- Option de protection de l'héritage réservant un pourcentage de la valeur
- Remboursements partiels facultatifs jusqu'à 10 % par an
- Protection en cas de déménagement vers un logement plus petit après cinq ans
Le produit en détail
A lifetime mortgage is a loan secured on a home, with no monthly payment required and no fixed end date. Interest is added to the balance instead of being paid, so the debt grows; it is repaid when the last borrower dies or moves into long-term care and the property is sold. The rate is fixed for life, and a no negative equity guarantee means the estate can never owe more than the property sells for.
Advantage Options is the version for clients who are confident the plan is permanent. It trades flexibility for price: a lower fixed rate, in exchange for a shorter early repayment window and a tighter loan-to-value than the rest of the range. A client who might repay early is being asked to pay for that option elsewhere, and should be.
Two protections deserve to be explained rather than listed. Inheritance protection ring-fences a stated percentage of the property’s eventual sale value, so a client can guarantee something passes on — at the cost of borrowing less today. Downsizing protection, available after five years, allows the loan to be repaid without an early repayment charge if the client moves to a smaller property that does not meet the lending criteria.
And the optional partial repayments of up to 10% a year are the most under-used feature in the whole range. A client who pays a little of the interest each year changes the compounding materially, and the chart below is drawn to show by how much.
Documentation
La documentation produit est remise aux intermédiaires accrédités. Demandez-la à votre souscripteur, ou demandez-la via le formulaire de demande.
- Illustration des données clésSur demande
- Barème des fraisSur demande
- Guide du courtierSur demande
Comment cela fonctionne
Ce qui se passe, dans l'ordre
De la première demande jusqu'à la mise en place de la garantie, du contrat ou de la ligne.
A broker establishes suitability and the amount
Minimum age 55, minimum property value £100,000, loan to value up to 41% depending on the youngest borrower’s age. Equity release is advised business and reaches us through a broker.
The property is valued and the offer issued
With a Key Facts Illustration showing the rate, the projected balance and the charges. That document, not this page, carries the figures for a real case.
The loan completes and the rate is fixed for life
No monthly payment is required. Interest is added to the balance.
Optional partial repayments, up to 10% a year
Voluntary, with no charge, and they compound in the client’s favour rather than the lender’s.
Repayment on death or long-term care
From the sale of the property, subject to the no negative equity guarantee. Downsizing protection applies after five years.
Les chiffres
Un exemple chiffré
Des calculs donnés à titre indicatif, pour que la structure du produit se voie plutôt qu'elle se décrive. Rien ici n'est une offre ni une projection.
£100,000 released against a £300,000 home
A client of 68, at an illustrative 6.5% fixed for life, with property growth assumed at 2% a year. The compounding is exact arithmetic on those assumptions.
- Property value at outset
- £300,000
- Released33% loan to value
- £100,000
- Illustrative fixed rate
- 6.5% a year, rolled up
- Balance after 10 years
- £187,714
- Balance after 20 years
- £352,365
- Property value after 20 years, at an assumed 2%
- £445,784
- Equity remaining after 20 years
- £93,419
- With partial repayments of 3% a year, balance at 20 yearsAbout £3,000 to £6,500 a year, and it halves the roll-up
- £217,000
Illustrative. The rate and the assumed property growth are illustrations, not forecasts, and a real case is quoted in a Key Facts Illustration with the actual rate, charges and projections. The no negative equity guarantee means the estate can never owe more than the sale proceeds even if property values fall.
Loan balance against property value
The illustrative case above: 6.5% rolled up, property growing at an assumed 2% a year.
Voir ces chiffres sous forme de tableau
| Property value, at an assumed 2% | Loan balance, rolled up at 6.5% | |
|---|---|---|
| Year 0 | £300,000 | £100,000 |
| Année 5 | £331,224 | £137,009 |
| Année 10 | £365,698 | £187,714 |
| Année 15 | £403,761 | £257,184 |
| Année 20 | £445,784 | £352,365 |
Adéquation
Où Advantage Options trouve sa place
Les cas auxquels il répond, ceux auxquels il ne répond pas, et ce qu'un souscripteur demande avant de tarifer.
C'est la bonne réponse lorsque
- Clients from 55 who are confident the arrangement is permanent.
- Cases where the lower fixed rate is worth a tighter early repayment window.
- Clients who want to ring-fence part of the value for their family through inheritance protection.
Il faut regarder ailleurs lorsque
- A client who may need capital in stages — Capital Select Options charges interest on drawn funds only.
- A client whose health might support a higher release — Lifestyle Select Options is underwritten for that.
- Anyone likely to repay early, given the shorter early repayment window.
Ce qu'il nous faut pour tarifer
- 1.The broker’s suitability assessment, and the clients’ ages.
- 2.Property details, tenure and an estimated value; minimum £100,000.
- 3.The amount required, and whether inheritance protection is wanted.
Questions
Ce que les courtiers nous demandent sur ce produit
Can the estate ever owe more than the house is worth?
No. The no negative equity guarantee caps the debt at the net sale proceeds of the property.
How much difference do partial repayments really make?
A great deal, because they act on a compounding balance. On the illustrative case above, paying roughly 3% a year brings the twenty-year balance down from about £352,000 to about £217,000.
What does inheritance protection cost?
It reduces the amount available to borrow today, because a ring-fenced percentage of the eventual sale value is no longer security for the loan. The Key Facts Illustration shows both figures side by side.
What happens if the client wants to move?
The loan can generally be transferred to a suitable new property. Downsizing protection, available after five years, allows repayment without an early repayment charge where the new property does not meet the lending criteria.
Financement immobilier
Autres produits de cette gamme
Demander des informations
Interrogez-nous sur Advantage Options
Le formulaire parvient à un souscripteur à Dublin. Si vous êtes intermédiaire, dites-le et nous l'orienterons vers le bureau courtiers.