Retraite
Retraites à prestations définies
Administration courante et paie des régimes à prestations définies qui restent gérés par leurs trustees, y compris la paie des retraités, les revalorisations et les demandes des affiliés.
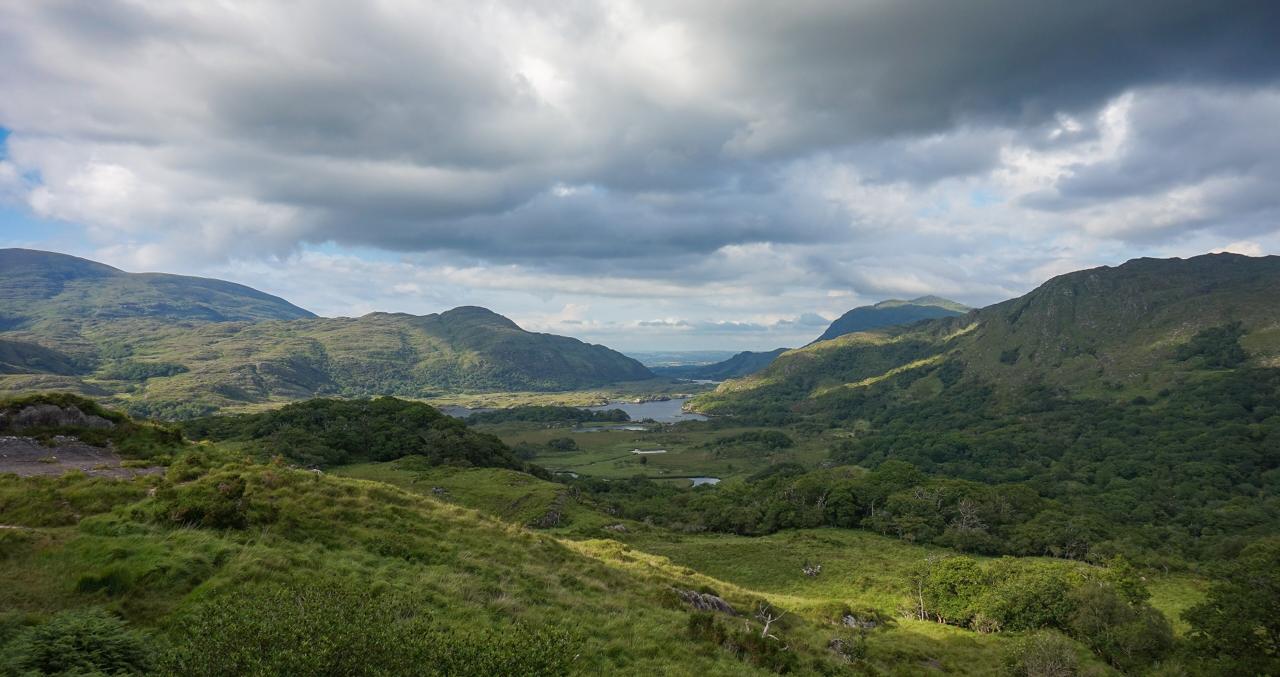
Ladies View, comté de Kerry · Marco Ober, CC BY-SA 4.0
À qui il s'adresse
Trustees de régimes à prestations définies en cours
Ce qu'il fait
- Paie des retraités et campagnes annuelles de revalorisation
- Assistance téléphonique aux affiliés assurée en Irlande
- Production de l'information réglementaire et des relevés de prestations
- Interface actuarielle pour les évaluations triennales
Le produit en détail
Not every defined benefit scheme is heading for a buy-out. Many will run for decades, and while they do somebody has to pay the pensioners on the right day, apply the right increase each April, produce the statutory disclosures, and answer the member who telephones to ask what happens to their spouse.
This is that service. Pensioner payroll runs monthly with an annual increase run; the increase basis is applied per benefit tranche, because a scheme that has been through several rule changes rarely increases everything the same way. Statutory disclosure and benefit statement production are handled on the scheme’s own timetable, and the actuarial liaison for triennial valuations is part of the job rather than an extra.
The member helpline is staffed in Ireland, by people who can see the scheme’s own rules. That is the part trustees notice: a member query answered correctly first time does not become a complaint, and a complaint is far more expensive than the call.
Documentation
La documentation produit est remise aux intermédiaires accrédités. Demandez-la à votre souscripteur, ou demandez-la via le formulaire de demande.
- Description du serviceSur demande
- Liste de contrôle de la transitionSur demande
Comment cela fonctionne
Ce qui se passe, dans l'ordre
De la première demande jusqu'à la mise en place de la garantie, du contrat ou de la ligne.
Transition from the incumbent administrator
Data, rules, benefit specifications, payroll history and open cases, against a checklist agreed with the trustees.
Monthly pensioner payroll
Payments, deductions and reconciliation, with the bank file and the control totals reported each month.
The annual increase run
Applied per benefit tranche under the scheme’s own rules, with the calculation evidenced for the trustees before it is paid.
Disclosure, statements and member queries
Statutory disclosure on the scheme timetable, benefit statements, and a Dublin-based helpline that can see the rules.
Quarterly trustee pack, and valuation support
Membership movements, payroll totals, case turnaround and open items — plus the data extracts the scheme actuary needs at each triennial valuation.
Les chiffres
Un exemple chiffré
Des calculs donnés à titre indicatif, pour que la structure du produit se voie plutôt qu'elle se décrive. Rien ici n'est une offre ni une projection.
An annual increase run on a 900-member scheme
Why the increase run is a per-tranche calculation rather than one percentage. Illustrative figures.
- Pensioners in payment
- 900
- Annual pensioner payroll
- £8,100,000
- Tranche A — pre-1997, discretionaryNo guaranteed increase under the rules
- 0.0%
- Tranche B — 1997 to 2005, capped at 5%
- 3.1%
- Tranche C — post-2005, capped at 2.5%
- 2.5%
- Weighted increase across the payroll
- 2.2%
- Additional annual payroll cost
- £178,200
Illustrative. A scheme that has been through several rule changes increases each tranche on its own basis, which is why a single headline percentage is almost always wrong and why the calculation is evidenced to the trustees before it is paid.
The payroll, split by increase basis
The illustrative £8.1m payroll above, divided into the tranches the increase run has to treat separately.
Annual pensioner payroll
£8,100,000
- Post-2005, capped at 2.5%£2,835,000 · 35%Increased at 2.5% in this run
- 1997 to 2005, capped at 5%£3,240,000 · 40%Increased at 3.1%
- Pre-1997, discretionary£2,025,000 · 25%No guaranteed increase
Voir ces chiffres sous forme de tableau
| Montant | Part | |
|---|---|---|
| Post-2005, capped at 2.5% — Increased at 2.5% in this run | £2,835,000 | 35.0% |
| 1997 to 2005, capped at 5% — Increased at 3.1% | £3,240,000 | 40.0% |
| Pre-1997, discretionary — No guaranteed increase | £2,025,000 | 25.0% |
| Annual pensioner payroll | £8,100,000 | 100% |
Adéquation
Où Retraites à prestations définies trouve sa place
Les cas auxquels il répond, ceux auxquels il ne répond pas, et ce qu'un souscripteur demande avant de tarifer.
C'est la bonne réponse lorsque
- Ongoing defined benefit schemes with 150 members or more.
- Trustees who want the helpline answered by people who can see the rules.
- Schemes whose increase bases differ by tranche and need the calculation evidenced.
Il faut regarder ailleurs lorsque
- Schemes about to buy out — Bulk Annuities is the route for those.
- Schemes below 150 members, where the fixed cost of the service is hard to justify.
Ce qu'il nous faut pour tarifer
- 1.Trust deed and rules, with all amending deeds.
- 2.Member and pensioner data, and the payroll history.
- 3.The benefit specification, the increase bases per tranche, and the disclosure timetable.
Questions
Ce que les courtiers nous demandent sur ce produit
Who answers member calls?
A Dublin-based team with access to the scheme’s own rules and records, not a general contact centre reading a script.
How long does a transition take?
It depends on the state of the incumbent’s data. The transition checklist sets out what we need, and the honest answer is that data quality decides the timetable.
Does the service include the actuarial valuation?
The liaison and the data extracts, yes. The valuation itself is the scheme actuary’s work.
Demander des informations
Interrogez-nous sur Retraites à prestations définies
Le formulaire parvient à un souscripteur à Dublin. Si vous êtes intermédiaire, dites-le et nous l'orienterons vers le bureau courtiers.