Jubilación
Pensiones de prestación definida
Administración continuada y nóminas de planes de prestación definida que permanecen con sus fiduciarios, incluida la nómina de pensionistas, las revalorizaciones y las consultas de los miembros.
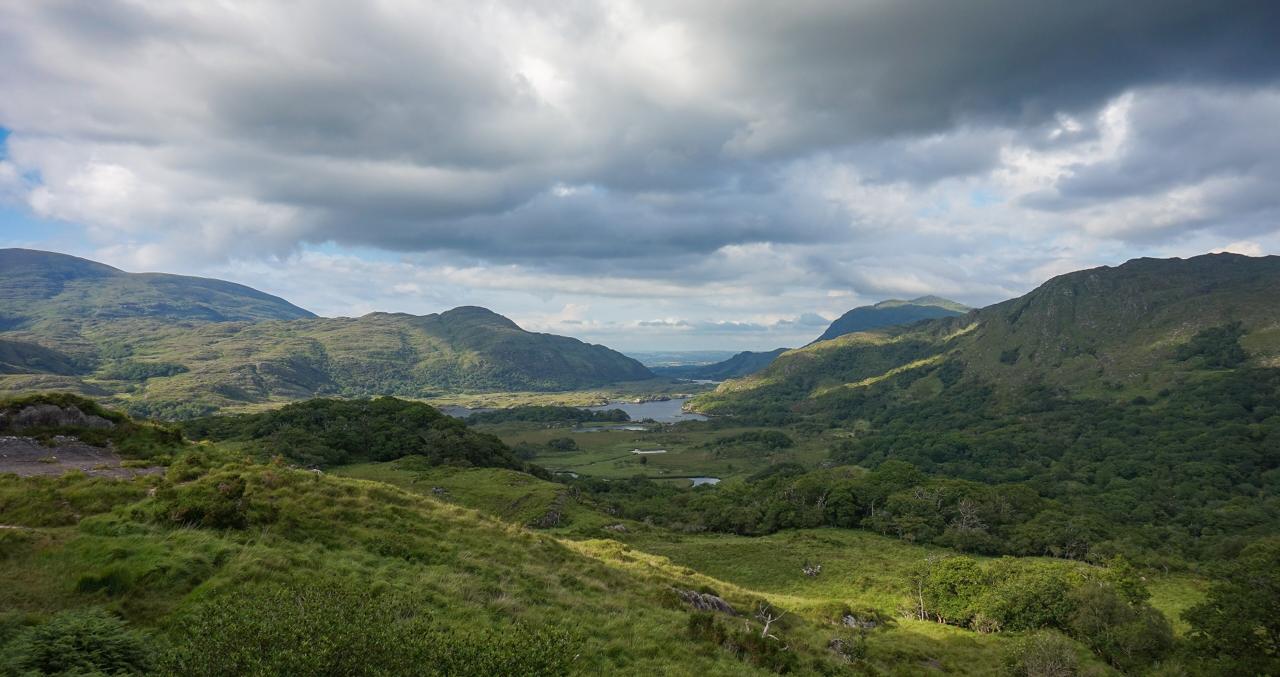
Ladies View, Co. Kerry · Marco Ober, CC BY-SA 4.0
Para quién es
Fiduciarios de planes de prestación definida en vigor
Qué hace
- Nómina de pensionistas y procesos anuales de revalorización
- Línea de ayuda para miembros atendida en Irlanda
- Elaboración de la información legal obligatoria y de los certificados de prestaciones
- Interlocución actuarial para las valoraciones trienales
El producto en detalle
Not every defined benefit scheme is heading for a buy-out. Many will run for decades, and while they do somebody has to pay the pensioners on the right day, apply the right increase each April, produce the statutory disclosures, and answer the member who telephones to ask what happens to their spouse.
This is that service. Pensioner payroll runs monthly with an annual increase run; the increase basis is applied per benefit tranche, because a scheme that has been through several rule changes rarely increases everything the same way. Statutory disclosure and benefit statement production are handled on the scheme’s own timetable, and the actuarial liaison for triennial valuations is part of the job rather than an extra.
The member helpline is staffed in Ireland, by people who can see the scheme’s own rules. That is the part trustees notice: a member query answered correctly first time does not become a complaint, and a complaint is far more expensive than the call.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Descripción del servicioA petición
- Lista de comprobación de la transiciónA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
Transition from the incumbent administrator
Data, rules, benefit specifications, payroll history and open cases, against a checklist agreed with the trustees.
Monthly pensioner payroll
Payments, deductions and reconciliation, with the bank file and the control totals reported each month.
The annual increase run
Applied per benefit tranche under the scheme’s own rules, with the calculation evidenced for the trustees before it is paid.
Disclosure, statements and member queries
Statutory disclosure on the scheme timetable, benefit statements, and a Dublin-based helpline that can see the rules.
Quarterly trustee pack, and valuation support
Membership movements, payroll totals, case turnaround and open items — plus the data extracts the scheme actuary needs at each triennial valuation.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
An annual increase run on a 900-member scheme
Why the increase run is a per-tranche calculation rather than one percentage. Illustrative figures.
- Pensioners in payment
- 900
- Annual pensioner payroll
- £8,100,000
- Tranche A — pre-1997, discretionaryNo guaranteed increase under the rules
- 0.0%
- Tranche B — 1997 to 2005, capped at 5%
- 3.1%
- Tranche C — post-2005, capped at 2.5%
- 2.5%
- Weighted increase across the payroll
- 2.2%
- Additional annual payroll cost
- £178,200
Illustrative. A scheme that has been through several rule changes increases each tranche on its own basis, which is why a single headline percentage is almost always wrong and why the calculation is evidenced to the trustees before it is paid.
The payroll, split by increase basis
The illustrative £8.1m payroll above, divided into the tranches the increase run has to treat separately.
Annual pensioner payroll
£8,100,000
- Post-2005, capped at 2.5%£2,835,000 · 35%Increased at 2.5% in this run
- 1997 to 2005, capped at 5%£3,240,000 · 40%Increased at 3.1%
- Pre-1997, discretionary£2,025,000 · 25%No guaranteed increase
Ver estas cifras en una tabla
| Importe | Proporción | |
|---|---|---|
| Post-2005, capped at 2.5% — Increased at 2.5% in this run | £2,835,000 | 35.0% |
| 1997 to 2005, capped at 5% — Increased at 3.1% | £3,240,000 | 40.0% |
| Pre-1997, discretionary — No guaranteed increase | £2,025,000 | 25.0% |
| Annual pensioner payroll | £8,100,000 | 100% |
Idoneidad
Dónde encaja Pensiones de prestación definida
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- Ongoing defined benefit schemes with 150 members or more.
- Trustees who want the helpline answered by people who can see the rules.
- Schemes whose increase bases differ by tranche and need the calculation evidenced.
Conviene mirar otra cosa cuando
- Schemes about to buy out — Bulk Annuities is the route for those.
- Schemes below 150 members, where the fixed cost of the service is hard to justify.
Lo que necesitamos para tarificar
- 1.Trust deed and rules, with all amending deeds.
- 2.Member and pensioner data, and the payroll history.
- 3.The benefit specification, the increase bases per tranche, and the disclosure timetable.
Preguntas
Lo que los corredores nos preguntan sobre este producto
Who answers member calls?
A Dublin-based team with access to the scheme’s own rules and records, not a general contact centre reading a script.
How long does a transition take?
It depends on the state of the incumbent’s data. The transition checklist sets out what we need, and the honest answer is that data quality decides the timetable.
Does the service include the actuarial valuation?
The liaison and the data extracts, yes. The valuation itself is the scheme actuary’s work.
Jubilación
Otros de esta gama
Solicitar información
Consúltenos sobre Pensiones de prestación definida
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.