Jubilación
Renta vitalicia y pensión del plan
Una renta garantizada pagadera durante el resto de la vida del partícipe, con revalorización opcional, un periodo garantizado y una pensión para el dependiente. Una vez en pago no puede modificarse.
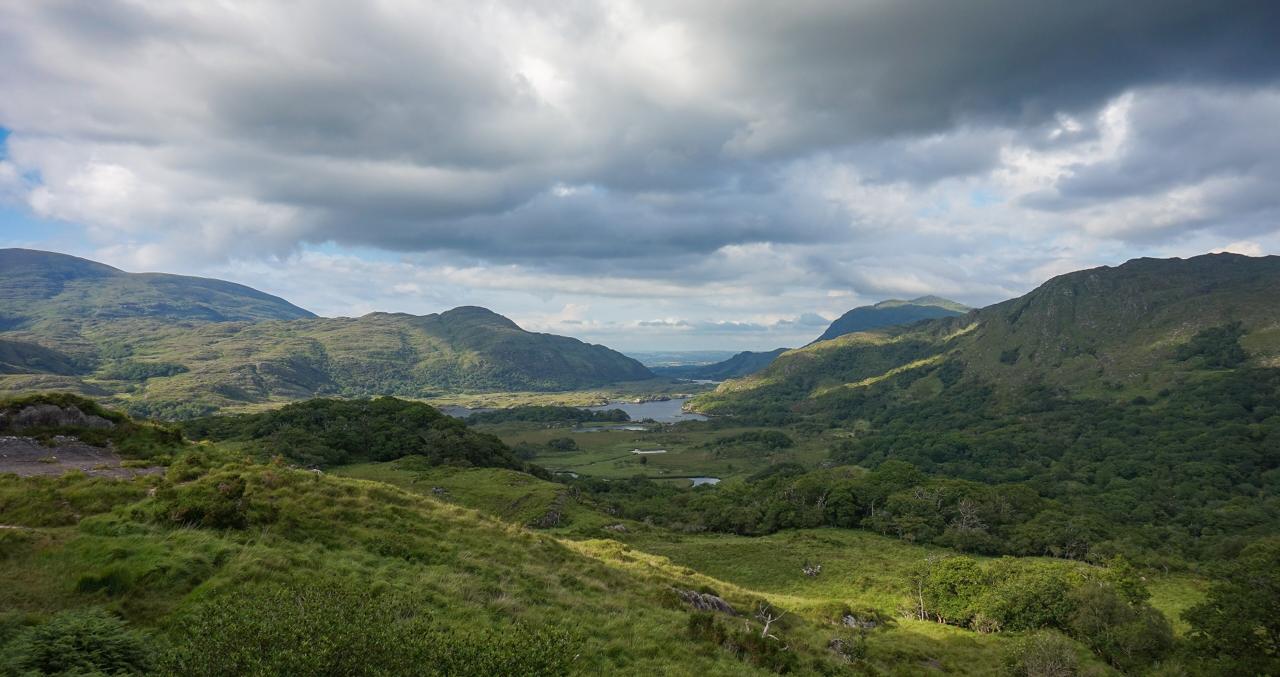
Ladies View, Co. Kerry · Marco Ober, CC BY-SA 4.0
Para quién es
Personas en el momento de la jubilación y partícipes de planes de empleo, a través de un corredor
Qué hace
- Renta constante, con crecimiento fijo o vinculada a un índice
- Periodo garantizado de hasta 30 años
- Pensión para dependientes del 50%, 66,7% o 100%
- Condiciones mejoradas cuando factores médicos o de estilo de vida reducen la esperanza de vida
El producto en detalle
A lifetime annuity converts a pension pot into an income that cannot run out. The insurer takes the capital and accepts the two risks the member cannot carry alone: that they live much longer than average, and that markets fall in the years they most need the money. In exchange the member gives up access to the capital and the ability to change their mind.
That trade is the whole product, and it is why the shape of the income matters more than the headline rate. A level income is highest at outset and lowest in real terms thirty years later. An escalating income starts materially lower and overtakes the level one somewhere in the second decade. Neither is right in general; which is right depends on how long the member lives, which nobody knows.
Three features soften the irrevocability without removing it. A guarantee period keeps payments running to the estate if the member dies early in the term. A dependant’s pension continues a proportion of the income to a spouse or partner for their life. And enhanced terms recognise that a member with a shortened life expectancy — through a medical condition, or through smoking — should be paid more, not less, for the same capital.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Documento de características principalesA petición
- Solicitud de oferta de renta vitaliciaA petición
- Cuestionario médicoA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
The pot and the shape are settled
Capital available, age, escalation basis, guarantee period, any dependant’s pension, and payment frequency. Each of these changes the price.
Health and lifestyle are underwritten
A medical questionnaire, and where relevant GP evidence. A shortened life expectancy buys a higher income, which is why the questionnaire is worth completing carefully rather than quickly.
A quotation is issued and held
For a stated period. Annuity rates move with long-dated yields, so a quotation is a snapshot rather than a standing offer.
The annuity is set up and paid
Monthly to annually, in advance or arrears, for life.
It does not change again
Once in payment the basis is fixed. There is no surrender value and no switch. That permanence is what the guarantee is made of, and it is the reason the decision is taken slowly.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
A £250,000 pot, level against escalating
Two shapes bought with the same capital, at an illustrative rate for a member aged 65. The comparison is the point; the rates themselves depend entirely on the day and the person.
- Pension pot applied
- £250,000
- Option A — level incomeIllustrative 6.0% at outset, and it never rises
- £15,000 a year
- Option B — income escalating at 3% a yearIllustrative 4.2% at outset, and it rises every year
- £10,500 a year
- Difference in year 1
- £4,500 in favour of level
- Option B overtakes option A in
- Year 13
- Cumulative payments by year 25 — level
- £375,000
- Cumulative payments by year 25 — escalating
- £383,000
Illustrative rates, not a quotation. Real annuity rates depend on age, health, postcode, the shape chosen and long-dated yields on the day of purchase. The escalating option costs 30% of the first year’s income to buy protection that only pays off if the member lives into their late seventies.
Level income against 3% escalation
Annual income from the same £250,000 pot, on the illustrative rates above.
Ver estas cifras en una tabla
| Level income | Escalating at 3% | |
|---|---|---|
| Year 1 | £15,000 | £10,500 |
| Year 5 | £15,000 | £11,816 |
| Año 10 | £15,000 | £13,699 |
| Year 15 | £15,000 | £15,882 |
| Year 20 | £15,000 | £18,413 |
| Year 25 | £15,000 | £21,347 |
Idoneidad
Dónde encaja Renta vitalicia y pensión del plan
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- A member who needs a floor under their essential spending and will not revisit the decision.
- Someone with a medical condition or lifestyle factor that improves the terms.
- A member with a dependant who must keep an income after the first death.
Conviene mirar otra cosa cuando
- A member who may need the capital back — an annuity has no surrender value.
- Someone who wants to keep investment exposure; the Flexible Income Annuity or drawdown is nearer.
- A member unwilling to fix a decision for life — the Fixed Term Income Plan defers it.
Lo que necesitamos para tarificar
- 1.Date of birth, and the pot available, with the ceding scheme’s details.
- 2.The shape wanted: escalation, guarantee period, dependant’s pension, frequency.
- 3.The medical questionnaire, and consent to approach the GP if enhanced terms are in play.
Preguntas
Lo que los corredores nos preguntan sobre este producto
What does a guarantee period actually guarantee?
That payments continue for that number of years whether or not the member survives them. A five-year guarantee on a member who dies in year two pays the remaining three years to the estate. It guarantees the payments, not the capital.
Why would a medical condition increase the income?
Because the price of a lifetime income is a view on how long it will be paid for. Where a condition shortens life expectancy, the same capital buys more income each year. It is the one part of the process where disclosing more usually helps the member.
Can the annuity be changed once it is in payment?
No. That is the deliberate design, not an oversight: the certainty the member is buying exists precisely because neither side can revisit it.
Is a level income always the wrong answer?
No. A member with other index-linked income, or one who expects to live an average rather than a long life, may reasonably prefer the higher payment now. The crossing point in the chart above is the argument, in both directions.
Jubilación
Otros de esta gama
Solicitar información
Consúltenos sobre Renta vitalicia y pensión del plan
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.