Jubilación
The Retirement Account
Una única cuenta que mantiene en paralelo un fondo de disposición flexible y un fondo de renta garantizada, para que el partícipe asegure el gasto esencial y deje el resto invertido sin tener que llevar dos contratos.
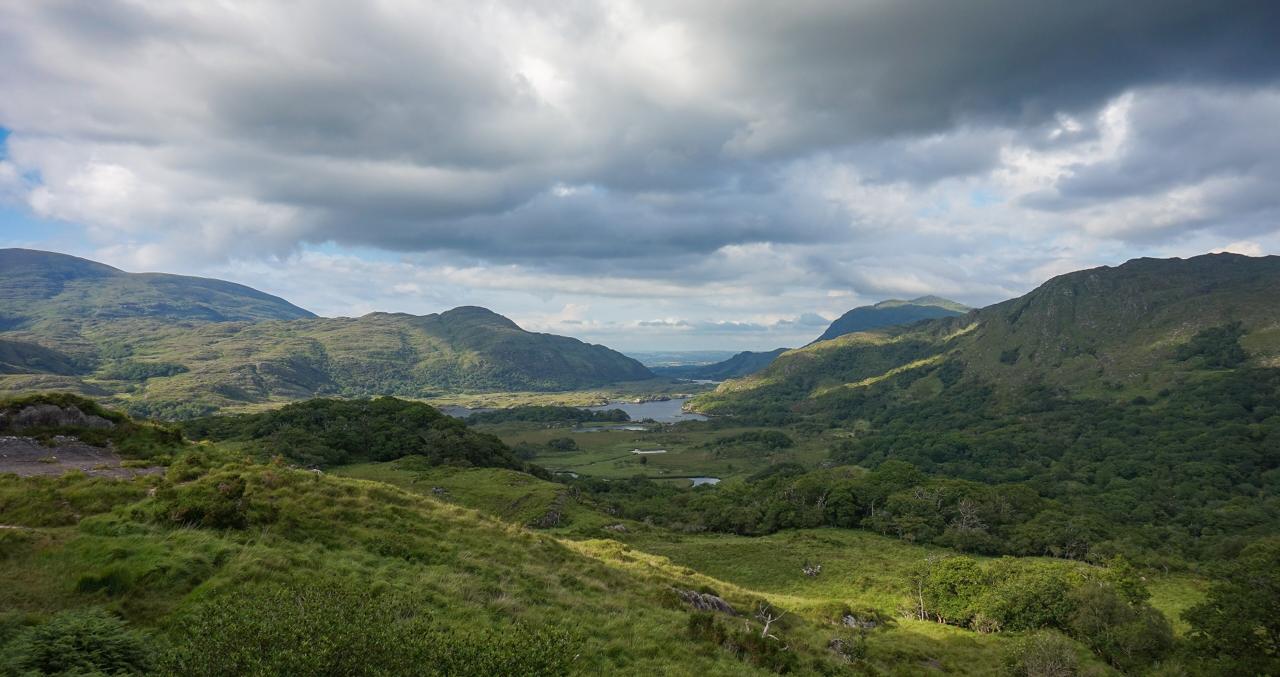
Ladies View, Co. Kerry · Marco Ober, CC BY-SA 4.0
Para quién es
Personas que construyen una renta de jubilación combinada
Qué hace
- Ahorro para la jubilación, disposición flexible y renta garantizada en una sola cuenta
- Traslada dinero al fondo garantizado por etapas a medida que el partícipe envejece
- Un único informe anual que cubre las dos bolsas
- Gamas de fondos básica y ampliada en la parte invertida
El producto en detalle
Most members reaching retirement do not want either pure certainty or pure flexibility; they want the mortgage, the heating and the food secured, and the rest invested. Historically that meant running two contracts with two providers, two statements and two sets of instructions, and reconciling them by hand.
The Retirement Account holds all of it in one place: a savings pot for contributions still being made, a drawdown pot that stays invested, and a guaranteed income pot that behaves like an annuity. Money can move from drawdown into the guaranteed pot in stages, which matters because annuity rates improve with age — securing income gradually through the sixties and seventies is usually better than doing it all on one day at 65.
One consolidated statement covers the lot. That is an administrative feature and also a suitability one: a member who can see the guaranteed floor and the invested remainder on the same page understands their own position, which is not always true of two statements from two providers.
Documentación
La documentación de producto se facilita a los intermediarios acreditados. Pídala a su suscriptor o solicítela mediante el formulario de consulta.
- Documento de características principalesA petición
- Guía de la gama de fondosA petición
- Solicitud de ilustraciónA petición
Cómo funciona
Qué ocurre, en orden
Desde la primera consulta hasta el momento en que la cobertura, el contrato o la línea queda en vigor.
The account is opened with a fund
From £10,000, transferred in or built from contributions to the savings pot.
Money is allocated between the pots
Savings, drawdown, and guaranteed income. The guaranteed pot has a £10,000 minimum each time it is used.
Income is taken from drawdown, or secured
Drawdown income is flexible and depends on the funds; the guaranteed pot pays a fixed income for life.
Further tranches are secured as the member ages
Each tranche is priced at the member’s age at the time. This is the feature the product is built around.
One statement reports everything
Annually, across all three pots.
Las cifras
Un ejemplo resuelto
Cálculos ilustrativos, para que la forma del producto se vea en lugar de describirse. Nada de lo que aquí figura es una oferta ni una proyección.
Securing income in three tranches
A £400,000 account, with income secured at 65, 70 and 75 rather than all at once. Illustrative rates only.
- Account value at 65
- £400,000
- Tranche 1 at age 65Illustrative 6.0%
- £100,000 → £6,000 a year
- Tranche 2 at age 70Illustrative 7.1% — the rate improves with age
- £100,000 → £7,100 a year
- Tranche 3 at age 75Illustrative 8.6%
- £100,000 → £8,600 a year
- Guaranteed income once all three are secured
- £21,700 a year
- Remaining in drawdown
- £100,000, still invested
- If all £300,000 had been secured at 65Illustrative 6.0% on the whole amount
- £18,000 a year
Illustrative rates, not a quotation, and the comparison ignores what the unsecured money earns or loses while it waits — which is the risk the member takes in exchange. Annuity rates rise with age because the expected payment period is shorter; they also move with long-dated yields, which is the part nobody can plan around.
Guaranteed income built in stages
Cumulative guaranteed income after each tranche, on the illustrative rates above.
Ver estas cifras en una tabla
| Valor | |
|---|---|
| At 65 | £6k |
| At 70 | £13.1k |
| At 75 | £21.7k |
| All at 65 — The same £300,000 secured on one day | £18k |
Idoneidad
Dónde encaja The Retirement Account
Los casos que resuelve, los que no, y lo que un suscriptor necesita antes de tarificar.
Es la respuesta adecuada cuando
- A member who wants a floor under essential spending and growth on the rest.
- Someone who expects to secure income gradually rather than in one decision.
- Cases where consolidating two contracts into one is worth doing in its own right.
Conviene mirar otra cosa cuando
- A member who wants the whole pot annuitised now — the Lifetime Annuity is simpler and cheaper.
- Someone who wants no guaranteed element at all.
Lo que necesitamos para tarificar
- 1.Date of birth, transfer details from the ceding scheme, and the fund available.
- 2.The initial split across the three pots, and the income required.
- 3.Fund selection for the invested side, and health information for any guaranteed tranche.
Preguntas
Lo que los corredores nos preguntan sobre este producto
Why do annuity rates improve with age?
Because the income is expected to be paid for fewer years. It is not a reward for waiting — it is the arithmetic of a shorter expected term, and it can be outweighed by a fall in yields while the member waits.
Can money move back out of the guaranteed pot?
No. A secured tranche is a lifetime income and is irrevocable, exactly as an annuity is. Movement is one way, from invested to guaranteed.
Is there a minimum for each tranche?
Yes, £10,000. It keeps each transaction large enough to be worth pricing and administering.
Jubilación
Otros de esta gama
Solicitar información
Consúltenos sobre The Retirement Account
El formulario llega a un suscriptor en Dublín. Si es intermediario, indíquelo y lo dirigiremos a la mesa de corredores.