Retraite
Rente viagère acquise
Une rente viagère constituée avec un capital qui n'est pas d'origine retraite — un héritage, une vente immobilière, une indemnité — dont une partie de chaque versement est traitée comme un remboursement de capital.
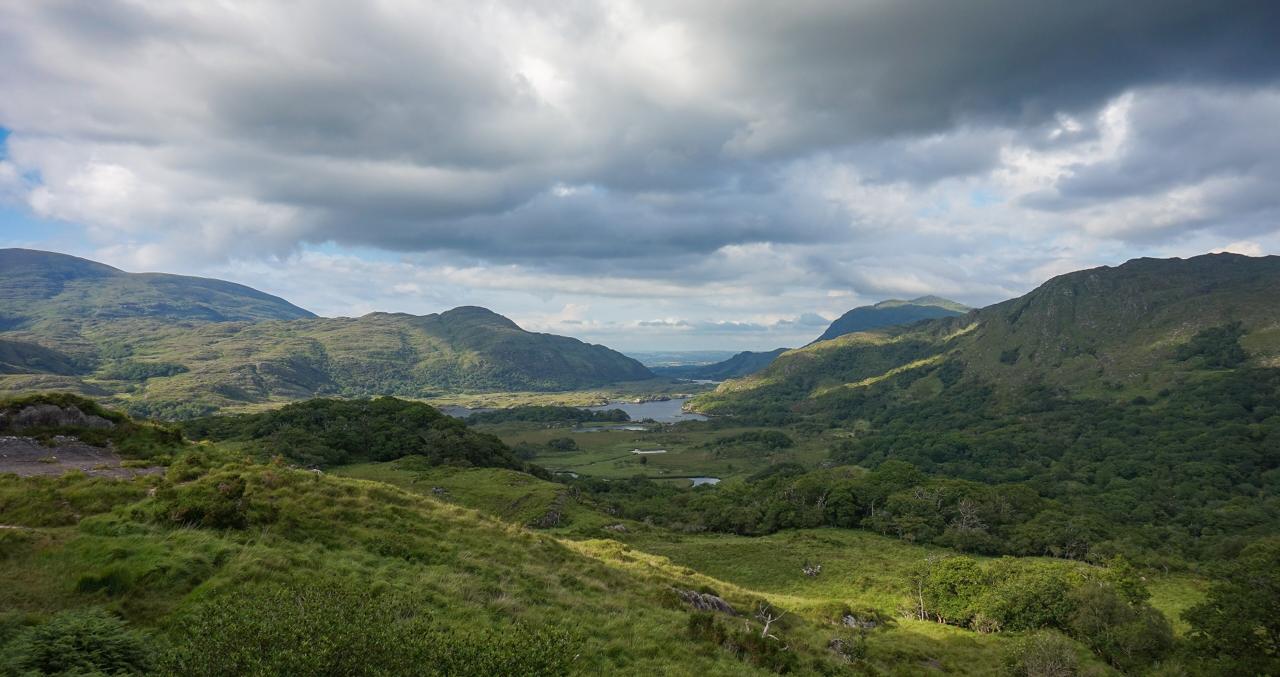
Ladies View, comté de Kerry · Marco Ober, CC BY-SA 4.0
À qui il s'adresse
Particuliers disposant d'un capital non retraite à convertir en revenu
Ce qu'il fait
- Constituée avec tout capital, et pas seulement des fonds de retraite
- Une partie de chaque versement est traitée comme un remboursement de capital
- Mêmes période garantie et options de réversion que la rente viagère
- Disponible à partir de 50 ans
Le produit en détail
A purchased life annuity does the same job as a pension annuity — a guaranteed income for life — but is bought with capital that was never in a pension. An inheritance, the proceeds of a property sale, a personal injury settlement or a business disposal can all be turned into income this way.
The structural difference is how each payment is regarded. Part of every instalment is treated as a return of the capital the member has already paid in, and part as interest. Because those two components are treated differently, the net position for a given gross income is generally better than the same income from pension money. How much better depends on the member’s age at purchase and on their own tax position, which is a matter for their adviser rather than for us.
The contract is available from age 50 — five years earlier than the pension annuity — because there is no pension access age to satisfy. Everything else, from guarantee periods to dependant’s pensions to enhanced underwriting, works exactly as it does on the lifetime annuity.
Documentation
La documentation produit est remise aux intermédiaires accrédités. Demandez-la à votre souscripteur, ou demandez-la via le formulaire de demande.
- Document sur les caractéristiques essentiellesSur demande
- Demande de tarificationSur demande
Comment cela fonctionne
Ce qui se passe, dans l'ordre
De la première demande jusqu'à la mise en place de la garantie, du contrat ou de la ligne.
The capital and its source are established
Non-pension money, with the usual source of funds evidence. Available from age 50.
The income shape is chosen
Level or escalating, guarantee period up to thirty years, and any dependant’s pension.
Health is underwritten
On the same basis as the lifetime annuity, with enhanced terms where life expectancy is shortened.
Income is paid for life, split into two parts
Each payment carries a capital element and an interest element, and the split is fixed at outset from the member’s age and the terms.
Les chiffres
Un exemple chiffré
Des calculs donnés à titre indicatif, pour que la structure du produit se voie plutôt qu'elle se décrive. Rien ici n'est une offre ni une projection.
A £200,000 property sale, converted to income
A member aged 68, on illustrative terms. The split shown is the mechanism this product exists for.
- Capital appliedProceeds of a property sale — not pension money
- £200,000
- Gross incomeIllustrative 6.5% at age 68
- £13,000 a year
- Treated as return of capital
- £8,400 a year
- Treated as interest
- £4,600 a year
- Paid monthly
- £1,083.33
- Guarantee period selected
- 10 years
Illustrative and not a quotation, and emphatically not tax advice. The capital and interest split is set at outset from the member’s age and the annuity terms; how each element is treated depends on the member’s own residence and circumstances, and belongs with their adviser.
What a year of income is made of
The £13,000 illustrative income above, split as the contract sets it.
Gross annual income
£13,000
- Return of capital£8,400 · 65%The member’s own money coming back
- Interest element£4,600 · 35%The return on capital still held
Voir ces chiffres sous forme de tableau
| Montant | Part | |
|---|---|---|
| Return of capital — The member’s own money coming back | £8,400 | 64.6% |
| Interest element — The return on capital still held | £4,600 | 35.4% |
| Gross annual income | £13,000 | 100% |
Adéquation
Où Rente viagère acquise trouve sa place
Les cas auxquels il répond, ceux auxquels il ne répond pas, et ce qu'un souscripteur demande avant de tarifer.
C'est la bonne réponse lorsque
- Non-pension capital that the member wants converted into a guaranteed income.
- Members aged 50 to 55, who cannot yet use a pension annuity.
- Cases where a settlement or a sale must produce a dependable income for life.
Il faut regarder ailleurs lorsque
- Pension money — that is the Lifetime Annuity.
- A member who may need the capital back.
Ce qu'il nous faut pour tarifer
- 1.Date of birth, the capital available and evidence of its source.
- 2.The income shape: escalation, guarantee period, dependant’s pension.
- 3.The medical questionnaire where enhanced terms may apply.
Questions
Ce que les courtiers nous demandent sur ce produit
How is the capital element decided?
From the member’s age and the annuity terms at purchase, and it is fixed for the life of the contract rather than recalculated each year.
Can pension money be used?
No. Pension funds buy a pension annuity, and the two are separate contracts with different rules.
Are enhanced terms available?
Yes, on the same basis as the lifetime annuity. Medical and lifestyle factors that shorten life expectancy increase the income.
Retraite
Autres produits de cette gamme
Demander des informations
Interrogez-nous sur Rente viagère acquise
Le formulaire parvient à un souscripteur à Dublin. Si vous êtes intermédiaire, dites-le et nous l'orienterons vers le bureau courtiers.