Planification patrimoniale
Wealth Preservation Account
Un contrat d'investissement placé en trust dès l'origine, de sorte que sa valeur sort de la succession du constituant après sept ans tout en restant accessible aux bénéficiaires à la discrétion des trustees.
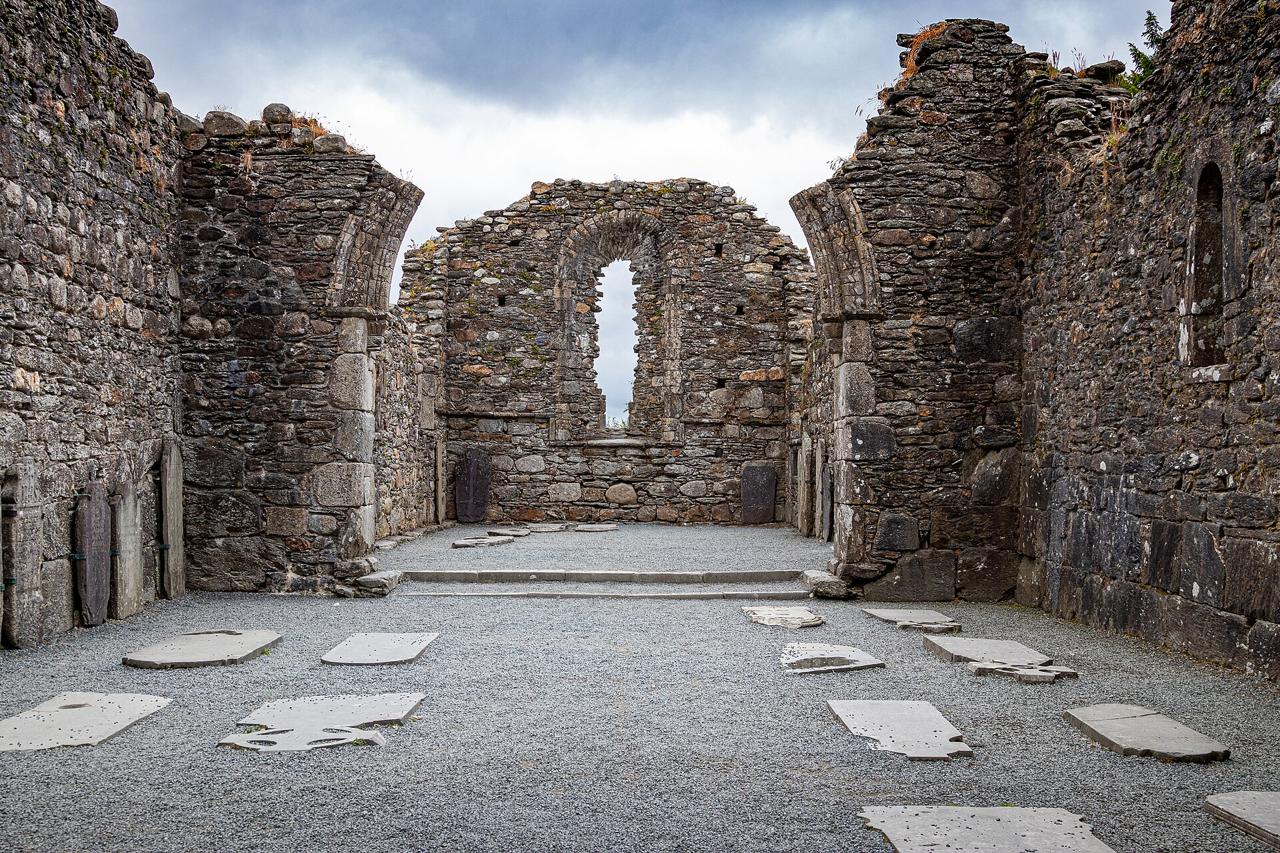
Glendalough, comté de Wicklow · Superbass, CC BY-SA 4.0
À qui il s'adresse
Clients présentés par un courtier effectuant des donations de capital de leur vivant
Ce qu'il fait
- Contrat et trust discrétionnaire signés ensemble
- La catégorie de bénéficiaires peut être modifiée par les trustees
- Segmenté pour la cession aux bénéficiaires
- Service de trustee professionnel disponible dès l'origine
Le produit en détail
The Wealth Preservation Account is an investment bond and a discretionary trust executed as one transaction. That matters more than it sounds: a bond written first and settled into trust later is two events with two dates and two sets of consequences, whereas a bond written in trust from the outset has one date — the date of the gift — and the clock starts there.
Inside the trust the bond behaves as a bond: segmented up to 99 policies, invested across the available range, and administered as one contract. Outside it, the trustees hold a discretionary power over a class of beneficiaries, which means nobody has a fixed entitlement and the trustees can respond to circumstances that nobody foresaw when the trust was written — a divorce, a bankruptcy, a beneficiary who should not receive capital at 25.
Segmentation and discretion work together. Because the bond is segmented, the trustees can assign whole policies to a beneficiary rather than encashing and distributing cash, which moves the asset itself. Whether that is the right route in any particular case is a question for the trust’s own advisers.
Documentation
La documentation produit est remise aux intermédiaires accrédités. Demandez-la à votre souscripteur, ou demandez-la via le formulaire de demande.
- Acte de trustSur demande
- Document sur les caractéristiques essentiellesSur demande
- Guide du trusteeSur demande
Comment cela fonctionne
Ce qui se passe, dans l'ordre
De la première demande jusqu'à la mise en place de la garantie, du contrat ou de la ligne.
The bond and the trust are executed together
One transaction, one date. The gift is the premium, and the seven-year clock runs from that date.
Trustees are appointed
The settlor’s own choice, or our Professional Trustee Service from outset. At least one trustee other than the settlor is the usual arrangement.
The bond is invested and segmented
Up to 99 policies, across the available fund range, held by the trustees.
The trustees exercise discretion
Over the beneficiary class, which they may vary within the terms of the deed. Decisions are minuted, because a discretionary power exercised without a record is hard to defend later.
Benefits are assigned or encashed
Whole segments assigned to a beneficiary, or encashed and distributed. The choice has consequences, and it belongs with the trust’s advisers.
Les chiffres
Un exemple chiffré
Des calculs donnés à titre indicatif, pour que la structure du produit se voie plutôt qu'elle se décrive. Rien ici n'est une offre ni une projection.
A £400,000 settlement, and the seven-year clock
What the trust holds and what the estate holds, at the date of the gift. Illustrative arithmetic, not a tax computation.
- Premium settled into trust
- £400,000
- Date of gift
- The date the bond and trust are executed together
- Segments issued
- 99
- Value per segment at outset
- £4,040.40
- Settlor’s right to the trust fund
- None
- Held outside the estate after
- 7 years from the date of gift
- Trustee power over the fund
- Discretionary, over the beneficiary class
Illustrative, and not tax advice. The seven-year rule stated here is the general mechanism a discretionary settlement engages; how it applies to a particular settlor depends on their domicile, their earlier gifts and their circumstances, and that is a matter for their own advisers.
What the trust holds, and what the estate holds
The illustrative £400,000 settlement above, at the date of gift and after seven years.
Voir ces chiffres sous forme de tableau
| Held by the trustees | Held in the settlor’s estate | |
|---|---|---|
| Before the gift — All in the estate | £0k | £400k |
| At the date of gift — Held by trustees, clock running | £400k | £0k |
| After 7 years — Clock complete | £400k | £0k |
Adéquation
Où Wealth Preservation Account trouve sa place
Les cas auxquels il répond, ceux auxquels il ne répond pas, et ce qu'un souscripteur demande avant de tarifer.
C'est la bonne réponse lorsque
- A client making a lifetime gift of £50,000 or more who does not need the capital back.
- Cases where the beneficiaries should not have fixed entitlements — young, unmarried, or circumstances likely to change.
- Settlors who want a professional trustee from the outset rather than a family member for twenty years.
Il faut regarder ailleurs lorsque
- A client who may need the capital — the Gift and Loan Trust keeps it repayable.
- A client who needs an income from the gifted money — that is the Discounted Gift Trust.
- Someone whose objective is avoiding probate delay rather than reducing the estate — that is the Probate Trust.
Ce qu'il nous faut pour tarifer
- 1.The settlor’s details, the premium and source of funds evidence.
- 2.The intended beneficiary class, and the trustees to be appointed.
- 3.Confirmation that the client has taken their own tax advice on the gift.
Questions
Ce que les courtiers nous demandent sur ce produit
Why execute the bond and the trust together?
Because it gives one date. A bond assigned into trust later is a separate transaction with its own consequences, and the sequence has to be right rather than convenient.
Can the settlor be a beneficiary?
No. Settlor access defeats the purpose of the settlement. A client who needs access should be looking at the Gift and Loan Trust or the Probate Trust instead.
Who registers the trust?
The trustees. We supply guidance on the registration requirements; the filing obligation is theirs, and the Professional Trustee Service coordinates it where we are appointed.
Planification patrimoniale
Autres produits de cette gamme
Demander des informations
Interrogez-nous sur Wealth Preservation Account
Le formulaire parvient à un souscripteur à Dublin. Si vous êtes intermédiaire, dites-le et nous l'orienterons vers le bureau courtiers.