Planification patrimoniale
Trust de donation et de prêt
Une petite donation constitue le trust, puis un prêt plus important sans intérêt est avancé aux trustees, de sorte que la plus-value s'accumule hors de la succession tandis que le prêt reste remboursable à vue.
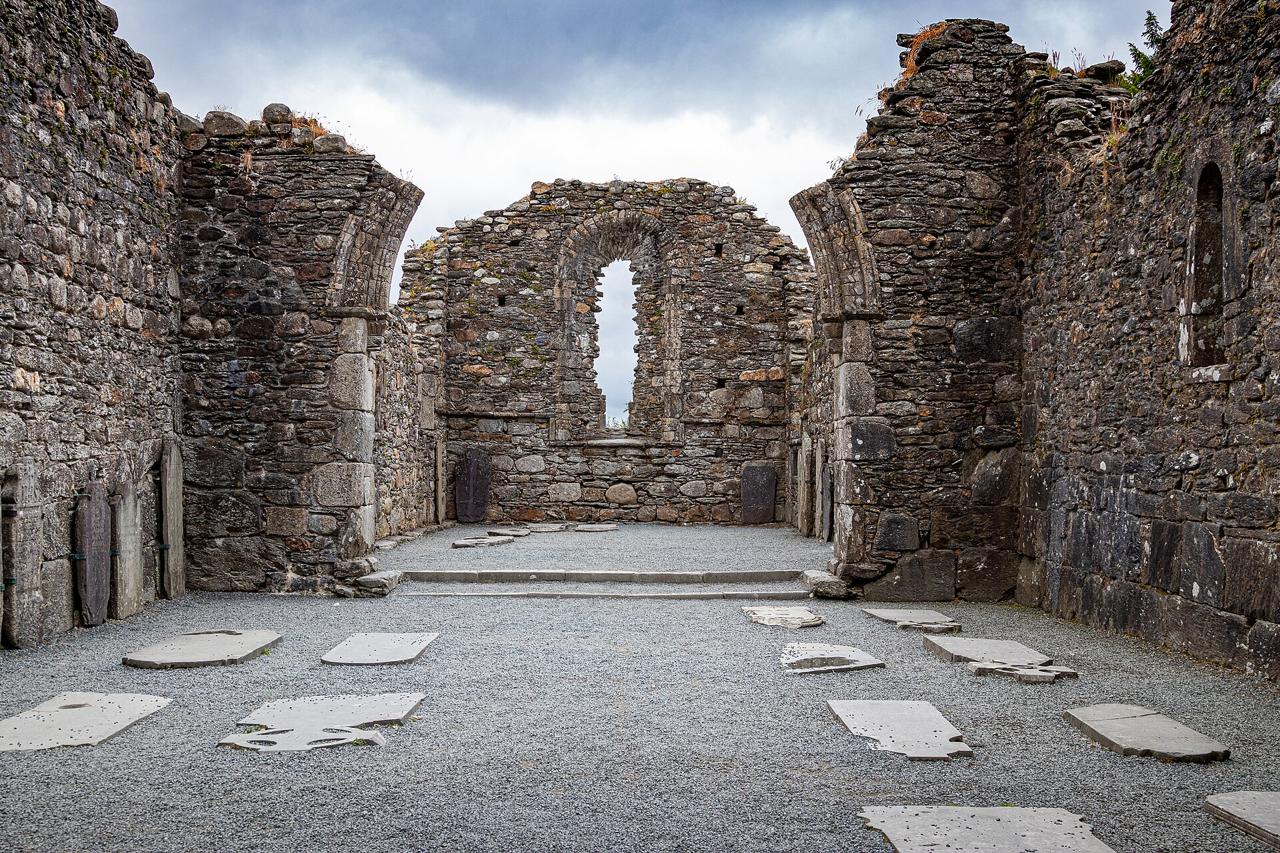
Glendalough, comté de Wicklow · Superbass, CC BY-SA 4.0
À qui il s'adresse
Clients présentés par un courtier qui ont besoin de récupérer leur capital mais pas sa plus-value
Ce qu'il fait
- Prêt remboursable au constituant à vue
- Seule la plus-value de l'investissement se situe hors de la succession
- Les remboursements du prêt peuvent être perçus sous forme de revenu régulier
- Le prêt en cours reste un actif de la succession
Le produit en détail
Many clients want the effect of a gift and cannot afford to make one. They are asset-rich and cautious: they would like the growth on £300,000 to accrue somewhere other than their estate, but they are not prepared to say goodbye to the £300,000 itself at 68 years old with thirty years of unknown care costs ahead.
The Gift and Loan Trust answers exactly that. A nominal gift establishes the trust. The settlor then advances a much larger sum to the trustees as an interest-free loan repayable on demand. The trustees invest it. Growth accrues in the trust and therefore outside the estate; the loan itself remains an estate asset, repayable in full whenever the settlor asks.
The trade is honest and should be stated plainly to clients: this structure moves the growth, not the capital. Its value builds slowly, in proportion to how well the trust fund does and how long it runs, and a settlor who takes the whole loan back in year three has achieved very little. The loan repayments can be taken as a regular stream, which is how most of these arrangements are actually used — an income from one’s own capital, with the growth accruing elsewhere.
Documentation
La documentation produit est remise aux intermédiaires accrédités. Demandez-la à votre souscripteur, ou demandez-la via le formulaire de demande.
- Acte du trust de donation et de prêtSur demande
- Contrat de prêtSur demande
- Guide du trusteeSur demande
Comment cela fonctionne
Ce qui se passe, dans l'ordre
De la première demande jusqu'à la mise en place de la garantie, du contrat ou de la ligne.
A nominal gift establishes the trust
A small sum — enough to constitute the trust — with the seven-year clock running on it alone.
The settlor lends the substantive amount
Interest free and repayable on demand, under a loan agreement executed with the deed.
The trustees invest the whole fund
Gift and loan together, typically in a segmented bond so that repayments can be met by encashing whole segments.
Loan repayments are taken as required
On demand, or as a regular stream. Each repayment returns estate property to the estate; it does not reduce what the trust has already grown.
The outstanding loan remains an estate asset
Whatever is unrepaid at death is owed to the estate. Only the growth is outside it.
Les chiffres
Un exemple chiffré
Des calculs donnés à titre indicatif, pour que la structure du produit se voie plutôt qu'elle se décrive. Rien ici n'est une offre ni une projection.
A £300,000 loan, ten years on
Illustrative growth of 4% a year, with £15,000 of loan repaid annually. The figures are arithmetic on an assumed rate, not a projection of what any fund will do.
- Nominal gift establishing the trust
- £100
- Interest-free loan advanced
- £300,000
- Annual loan repayments takenA 5% stream from the settlor’s own capital
- £15,000
- Repaid over ten years
- £150,000
- Loan still outstanding at year 10An estate asset — this part has not moved
- £150,000
- Trust fund at year 10, at an assumed 4%
- £268,000
- Trust value in excess of the outstanding loan
- £118,000
- That excess sits
- Outside the estate
Illustrative arithmetic on an assumed 4% growth rate, and not a projection. A lower rate produces a smaller excess and a negative rate produces none at all — the structure moves growth, so where there is no growth it moves nothing. Not tax advice.
The loan account against the trust fund
The illustrative arrangement above, at four points over ten years.
Voir ces chiffres sous forme de tableau
| Trust fund, at an assumed 4% | Loan outstanding to the estate | |
|---|---|---|
| Year 0 | £300,100 | £300,000 |
| Year 3 | £290,000 | £255,000 |
| Year 6 | £281,000 | £210,000 |
| Année 10 | £268,000 | £150,000 |
Adéquation
Où Trust de donation et de prêt trouve sa place
Les cas auxquels il répond, ceux auxquels il ne répond pas, et ce qu'un souscripteur demande avant de tarifer.
C'est la bonne réponse lorsque
- A client who wants the growth outside the estate but cannot part with the capital.
- Someone who needs a regular stream from their own money, taken as loan repayments.
- A long horizon — the benefit accrues with time and growth, and with nothing else.
Il faut regarder ailleurs lorsque
- A client who can afford an outright gift — the Gift Trust achieves more.
- A short horizon, or a client likely to demand full repayment early.
- A client who wants an immediate reduction in the estate — that is the Discounted Gift Trust.
Ce qu'il nous faut pour tarifer
- 1.The settlor’s details, the nominal gift and the loan amount.
- 2.The beneficiary class and the trustees.
- 3.The repayment pattern wanted, and confirmation of the client’s own tax advice.
Questions
Ce que les courtiers nous demandent sur ce produit
What if the settlor demands the whole loan back?
The trustees must repay it, which is what "on demand" means. They would encash trust investments to do so, and the trust continues holding whatever growth remains.
Can the trust refuse repayment?
No. That is the point — the loan is a genuine debt, and a structure where repayment were discretionary would not be a loan at all.
Why is the loan interest free?
Because interest paid to the settlor would return trust income to the estate and undermine the arrangement. The loan agreement records it explicitly.
What happens if the fund falls in value?
The loan is still repayable in full, and the trustees may have to repay from a fund worth less than the loan. That is the risk the settlor takes, and it should be discussed before the deed is signed rather than after.
Planification patrimoniale
Autres produits de cette gamme
Demander des informations
Interrogez-nous sur Trust de donation et de prêt
Le formulaire parvient à un souscripteur à Dublin. Si vous êtes intermédiaire, dites-le et nous l'orienterons vers le bureau courtiers.